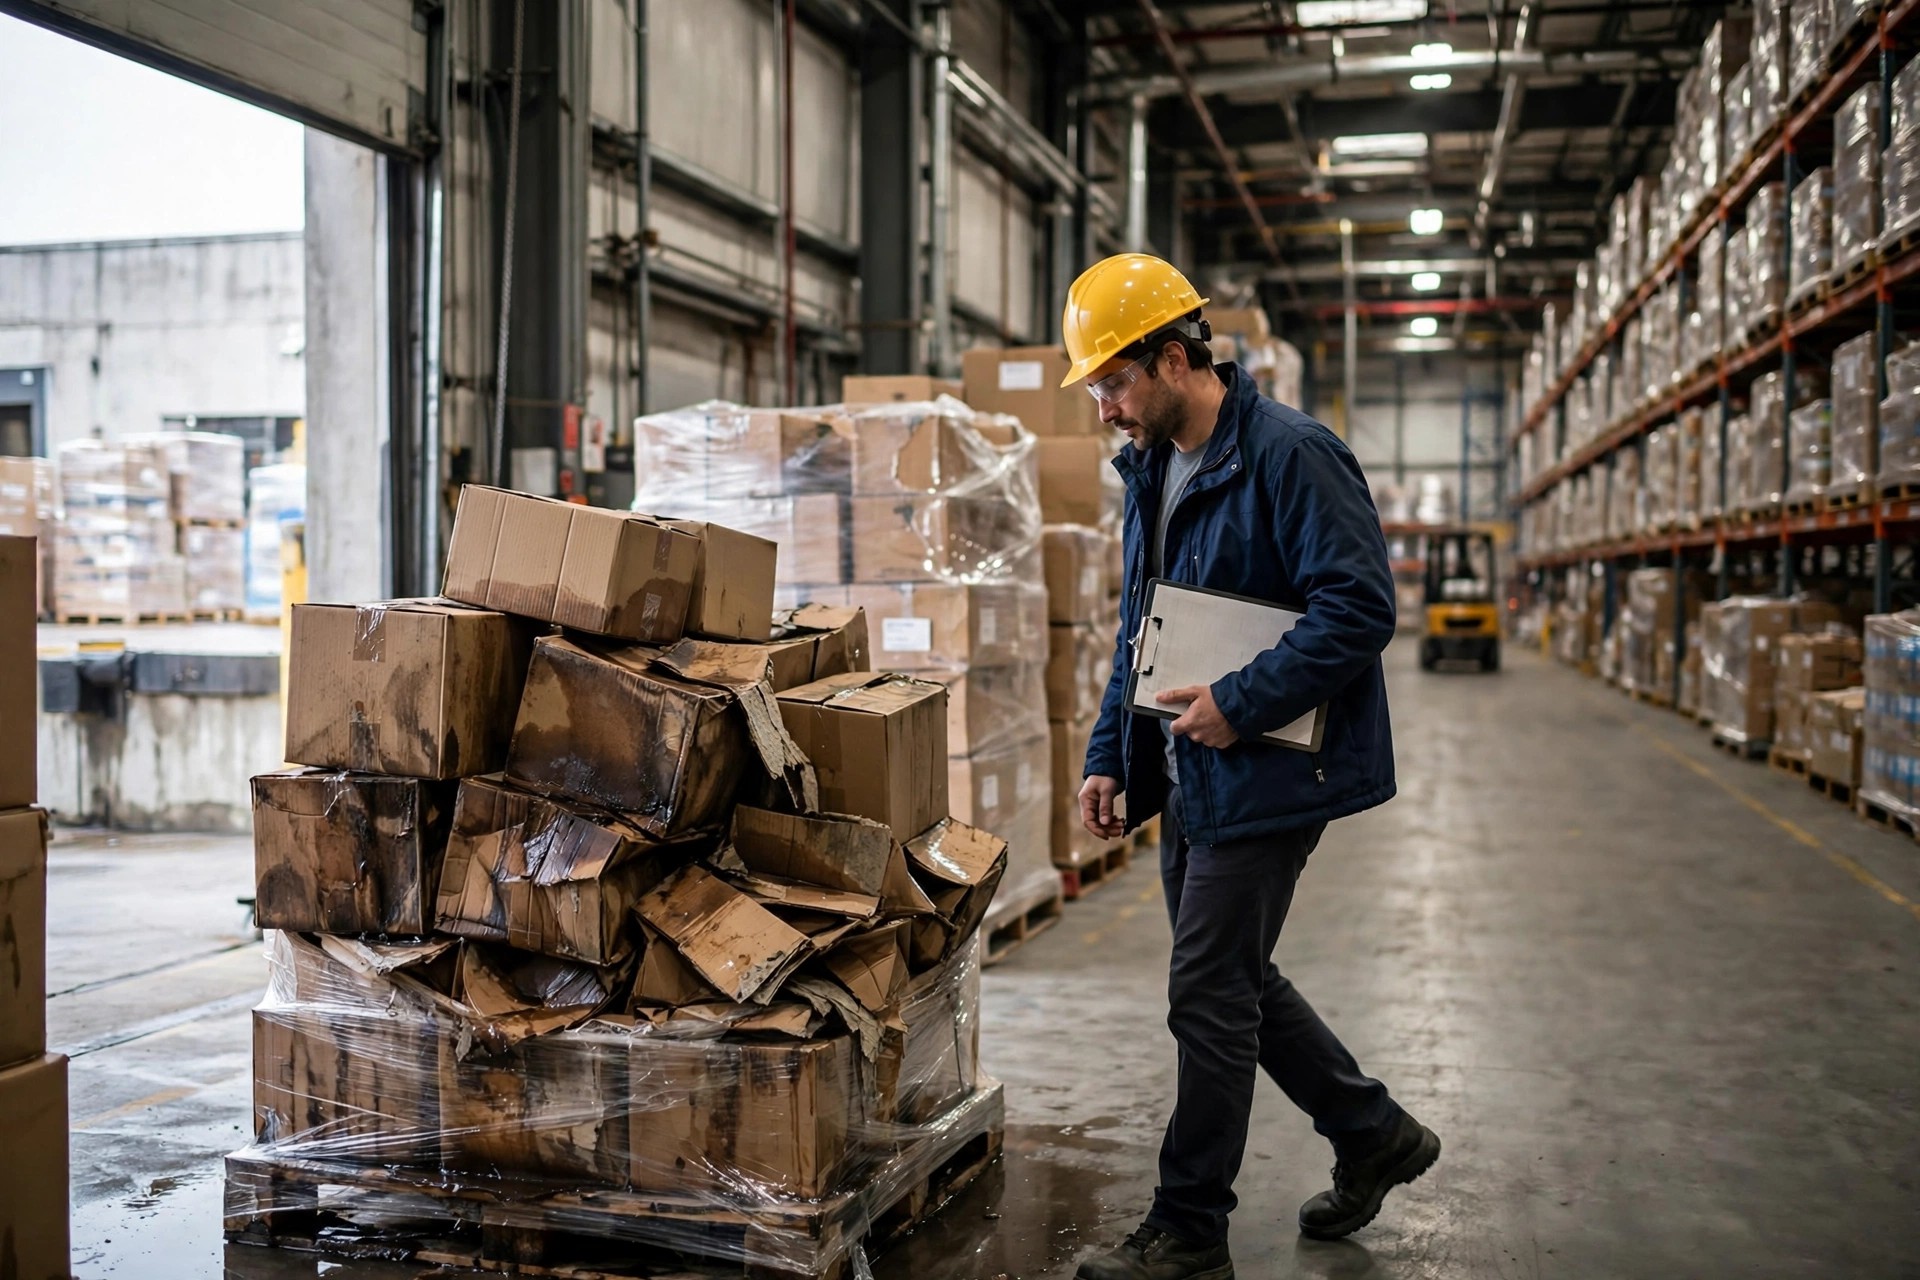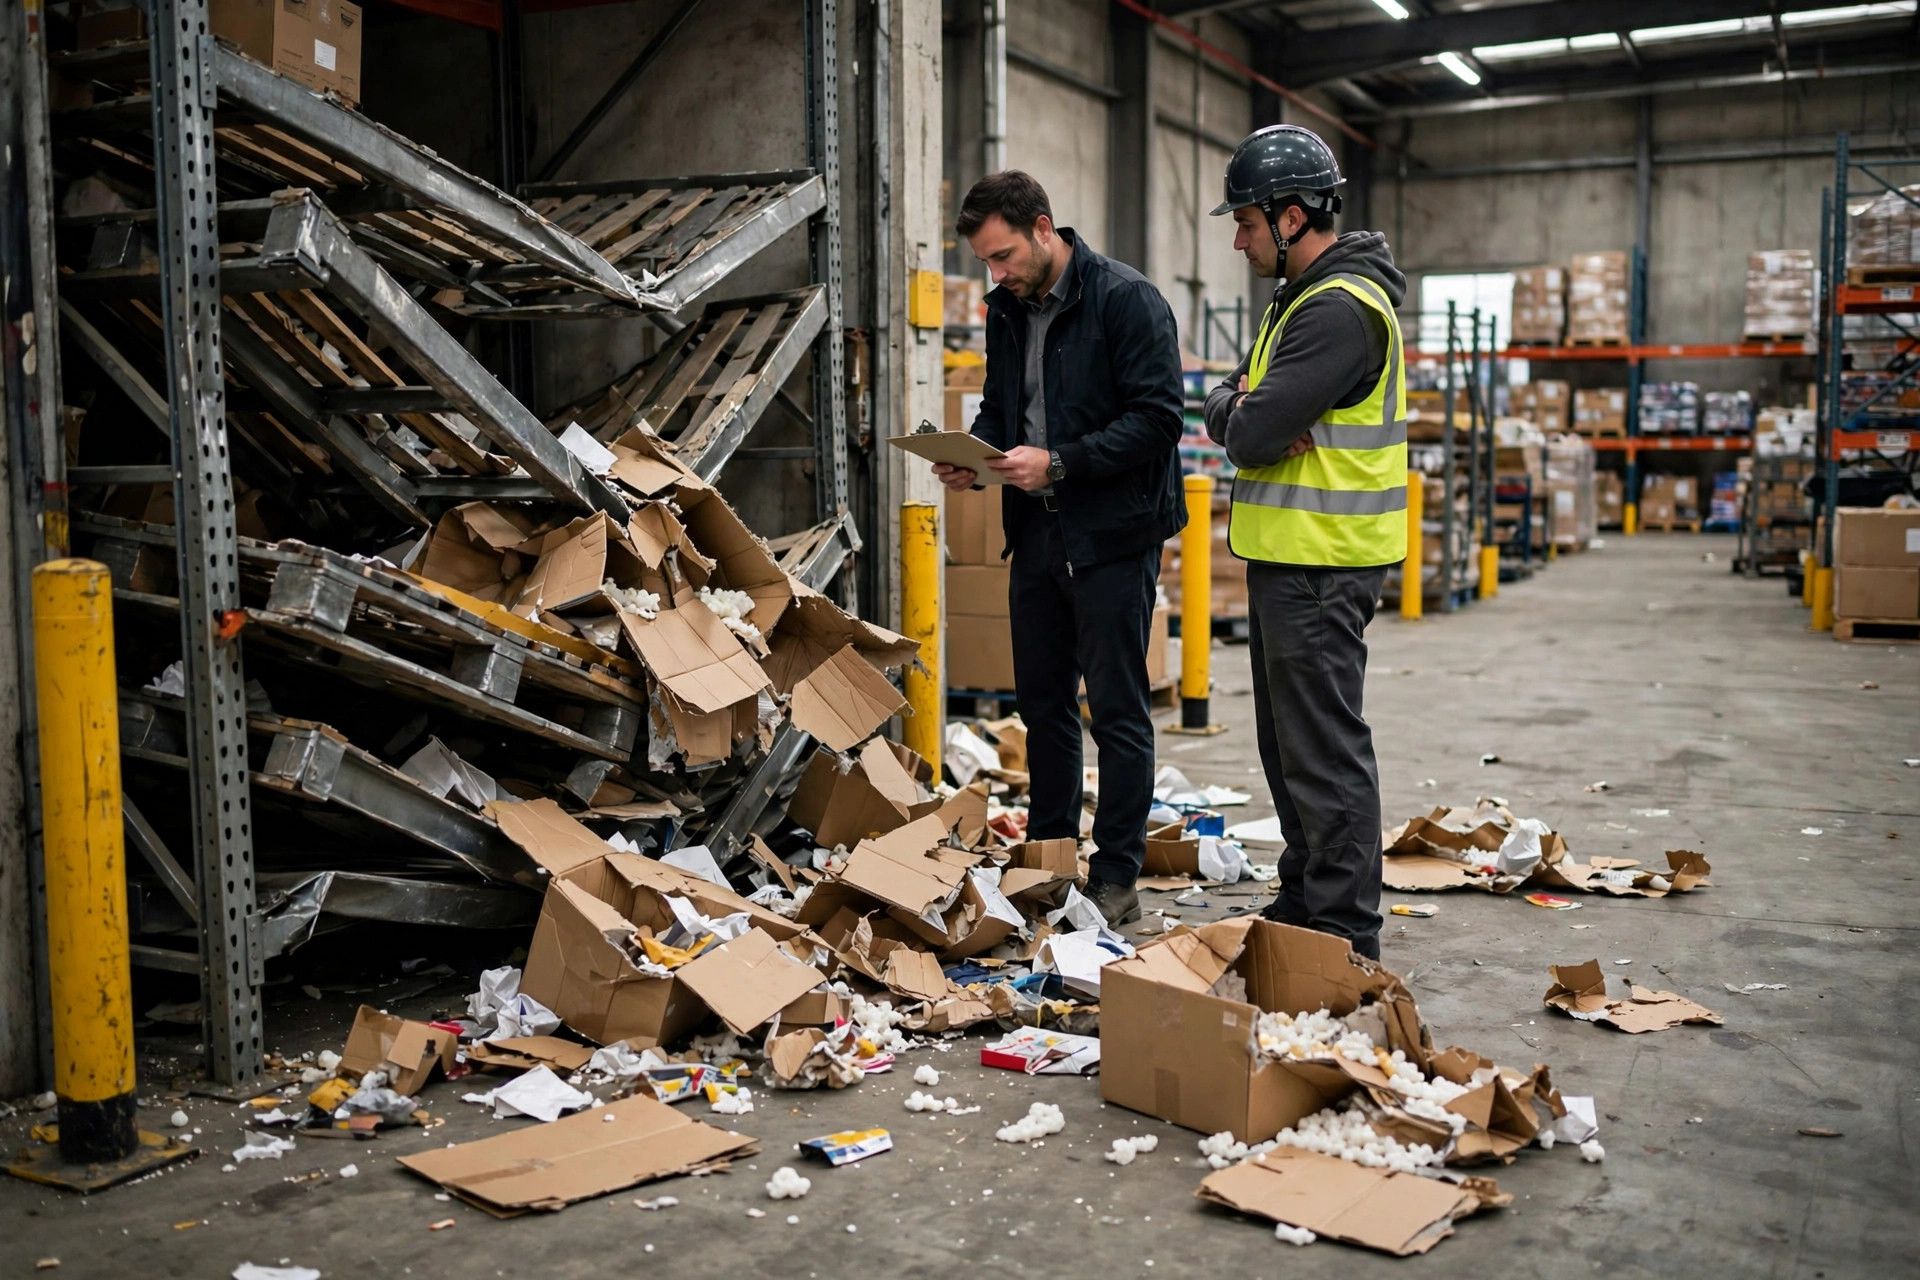
We have a client — September 2023, an 180,000-square-foot warehouse in the southwest suburbs of Chicago. A fire started above a dock door around midnight and burned through packaging materials and cartons on half a rack level. Not much product burned, but smoke got everywhere.
The client called the next morning: "Susan, the insurer is sending an adjuster. What do I prepare?" I said: "Get your documents ready. Everything in place, he signs off fast. Anything missing, he can drag you for three months."
He showed up with a policy copy and the claim receipt. The adjuster handed him a seven-document checklist, and he spent four months playing catch-up — recovering nearly 40% less than another client whose file was complete. Not dirty dealing — he'd handed away his own leverage.
Here are those 7 documents: what you need, where to find it, and what it costs you if it's missing. And remember — the first thing after a loss isn't calling your broker. It's securing the scene, photographing everything, and starting a draft of document number one.
1. The Policy and All Endorsements
What: The complete policy wording plus every endorsement. Not the two-page summary you skimmed when you signed — the full terms.
Where: Your broker always has a full set; so should finance and whoever owns insurance internally. Email the PDF to the ops and warehouse managers on day one of the policy — at 3 a.m. after a loss, you want it on your phone.
If it's missing: The adjuster's first question will always be "please provide the policy." Without it, he assesses your claim under the most conservative reading of the terms. Worse, you won't know whether your policy carries an automatic increase clause or a stock throughput clause. Warehouse inventory values swing — peak-season stock can be worth double the off-season level. Without the right provision, your loss gets calculated against the off-season average, and there's nothing you can say about it.
Here's the counterintuitive one: most people think the first call after a loss goes to the broker. It doesn't. First, secure the scene, photograph everything before it's touched, then check the policy for your deductible and reporting deadline. Many policies say "as soon as practicable" or "within 48 hours." Report one day late, and the adjuster can question whether the scene was disturbed. A client spent three days calming customers first — understandable — then filed. The report carried one line: "delayed notification." The carrier cut the payout by 15% on those two words.
2. Inventory Records Before and After the Loss
What: The inventory ledger from just before the loss (a WMS export or your latest cycle-count sheet) plus a damage inventory taken immediately after. The two side by side make the loss calculable.
Where: Export the day-before snapshot from your WMS, then walk the damaged zone and build a damaged-goods list — SKU, description, quantity, unit value, extent of damage, line by line.
If it's missing: Without the pre-loss ledger, the question becomes: "How do you prove this product was even in the building?" Customer claims 5,000 cases, you can account for 4,200 — the carrier won't pay a cent on the 800-case gap, and the customer comes after you. This is exactly why the "declared value" and "inventory reconciliation" clauses in your 3PL contract exist. Check whether yours actually spells them out.
Another client — February 2024, a Pennsylvania warehouse with a roof leak that soaked electronic components. He exported the WMS snapshot on loss day and finished the damage list by day three. Inspection done in two weeks, money in a month. The documents answered every question before he asked.
3. Scene Documentation: Photos and Video
What: Full coverage of the scene plus close-up details, photos with timestamps, continuous unedited video. First round before anything is moved, second round during cleanup.
Where: The warehouse manager's phone and CCTV exports — pull them now; footage typically rolls over every 30 to 90 days.
If it's missing: Photos are the adjuster's primary evidence for cause of loss. Without them he's working from your description, and where description and scene disagree, the report goes the unfavorable way. Clean up before photographing, and the carrier can question whether what you threw out was actually damaged.
4. Proof of Value
What: Purchase invoices for the damaged goods, receiving records, the shipper's declared value, recent sales contracts — whatever establishes what the goods were worth.
Where: Finance's purchase invoices, receiving records from the WMS, the declared-value attachment in your 3PL contract.
If it's missing: If you can't establish value, your goods get priced at the lowest defensible market price. Product bought for $12 a unit gets valued at $8 wholesale, and you eat the difference. A hard 3PL lesson: customers who under-declare value at receiving to save on premiums end up crying at claim time. An apparel client's customer declared 60% of value for years, then tried to claim 100% after a loss. The file showed three years of declarations: "We'll settle on the declared basis." The customer-is-king argument didn't survive that meeting.
5. Fire Protection and Security Records
What: Maintenance records for fire systems (sprinkler and smoke detector inspection reports), drill logs, security patrol records, alarm logs. For a fire, the fire department's incident report too.
Where: Facilities management and your fire-system vendor. The incident report comes from the local fire department — usually available in 15 to 30 days.
If it's missing: Your policy almost certainly requires working fire systems. Two smoke detectors with dead batteries and blank inspection logs? That's "failure to maintain" language the carrier can use to deny or discount. Our Chicago client paid exactly this price: two dead detectors, one note in the report, and the settlement ratio got squeezed.
6. Mitigation Expense Receipts
What: Every dollar spent to keep the loss from getting worse — emergency cleanup, temporary storage, reinforcement, rerouting. Keep every invoice.
Where: Procurement and admin payment records.
If it's missing: These costs are separately recoverable — sue and labor — since policies require reasonable steps to prevent further loss. Without documentation, nobody calculates them for you. A client with a burst water main spent $28,000 on overnight extraction and emergency relocation, fully documented — recovered to the last dollar. Most people don't even know this money is claimable.
7. Correspondence with Customers and Third Parties
What: Every email, message thread, and meeting note between you and your customers, your broker, and repair vendors after the loss — especially customer demand letters.
Where: Archived email, your ticketing system.
If it's missing: 3PL claims are often two-front wars: claim against the carrier on one side, defend against customer claims on the other. A customer's demand letter is the strongest corroboration you can hand the file. Conversely — if a customer emailed that "this batch was already moisture-damaged" and you filed it with the carrier anyway, that's fraud territory.
The 7-Document Checklist
| # | Document | Where to find it | Cost of missing it |
|---|---|---|---|
| 1 | Full policy + endorsements | Broker / finance | Terms read against you, conservatively |
| 2 | Pre- and post-loss inventory | WMS export + damage list | Can't prove goods were there; you absorb the gap |
| 3 | Scene photos/video + CCTV | Manager's phone / CCTV | Cause of loss written the unfavorable way |
| 4 | Proof of value | Invoices / declared value | Goods priced at market bottom |
| 5 | Fire & security maintenance logs | Facilities / fire department | "Failure to maintain" discounts your payout |
| 6 | Mitigation expense receipts | Payment records / invoices | Recoverable money out of your pocket |
| 7 | Correspondence trail | Email archive / ticketing | Two-front claim with no corroboration |
The Adjuster Is Human — You're Writing His Report for Him
Insider truth: the adjuster's report has to survive the carrier's internal review, and every number needs a basis. Complete file, and he writes freely — the report passes first round. Patchy documents, and he protects himself: everything uncertain becomes "questionable" or "pending verification," the report gets kicked back, and there go another two months. You're not fighting the adjuster. You're helping him write a report that can pass review.
So do this now, while nothing has happened: write down the "how to get it" path for each of these 7 documents in your emergency plan. Who gets the policy PDF, who exports the WMS snapshot, how long CCTV is retained — write it down, put it on the wall. At 3 a.m. on loss day, nobody figures this out from scratch.
Next time you negotiate a warehouse insurance policy, ask these three questions: one, exactly how many days is the reporting deadline, and what happens if you miss it; two, is there a stock fluctuation clause, and does coverage keep up when peak-season inventory value doubles; three, what's the cap on mitigation expense recovery, and does it require prior notice. Ask those three, and the broker will know he's dealing with an insider.
By Susan, 3PL Sales Director