A $2,000 parcel travels from Los Angeles to Dallas. For "coverage" you have four ways to pay: buy nothing, $0; declare value with UPS, $34.00; declare value with FedEx, $33.00; buy third-party shipping insurance, about $14.25. Same box, same lane — one option costs more than twice another, and what you can actually recover is not the same thing at all. No concepts in this piece, only arithmetic: UPS/FedEx declared value vs. real shipping insurance, line by line.
Bill #1: the declared value rate card (2026)
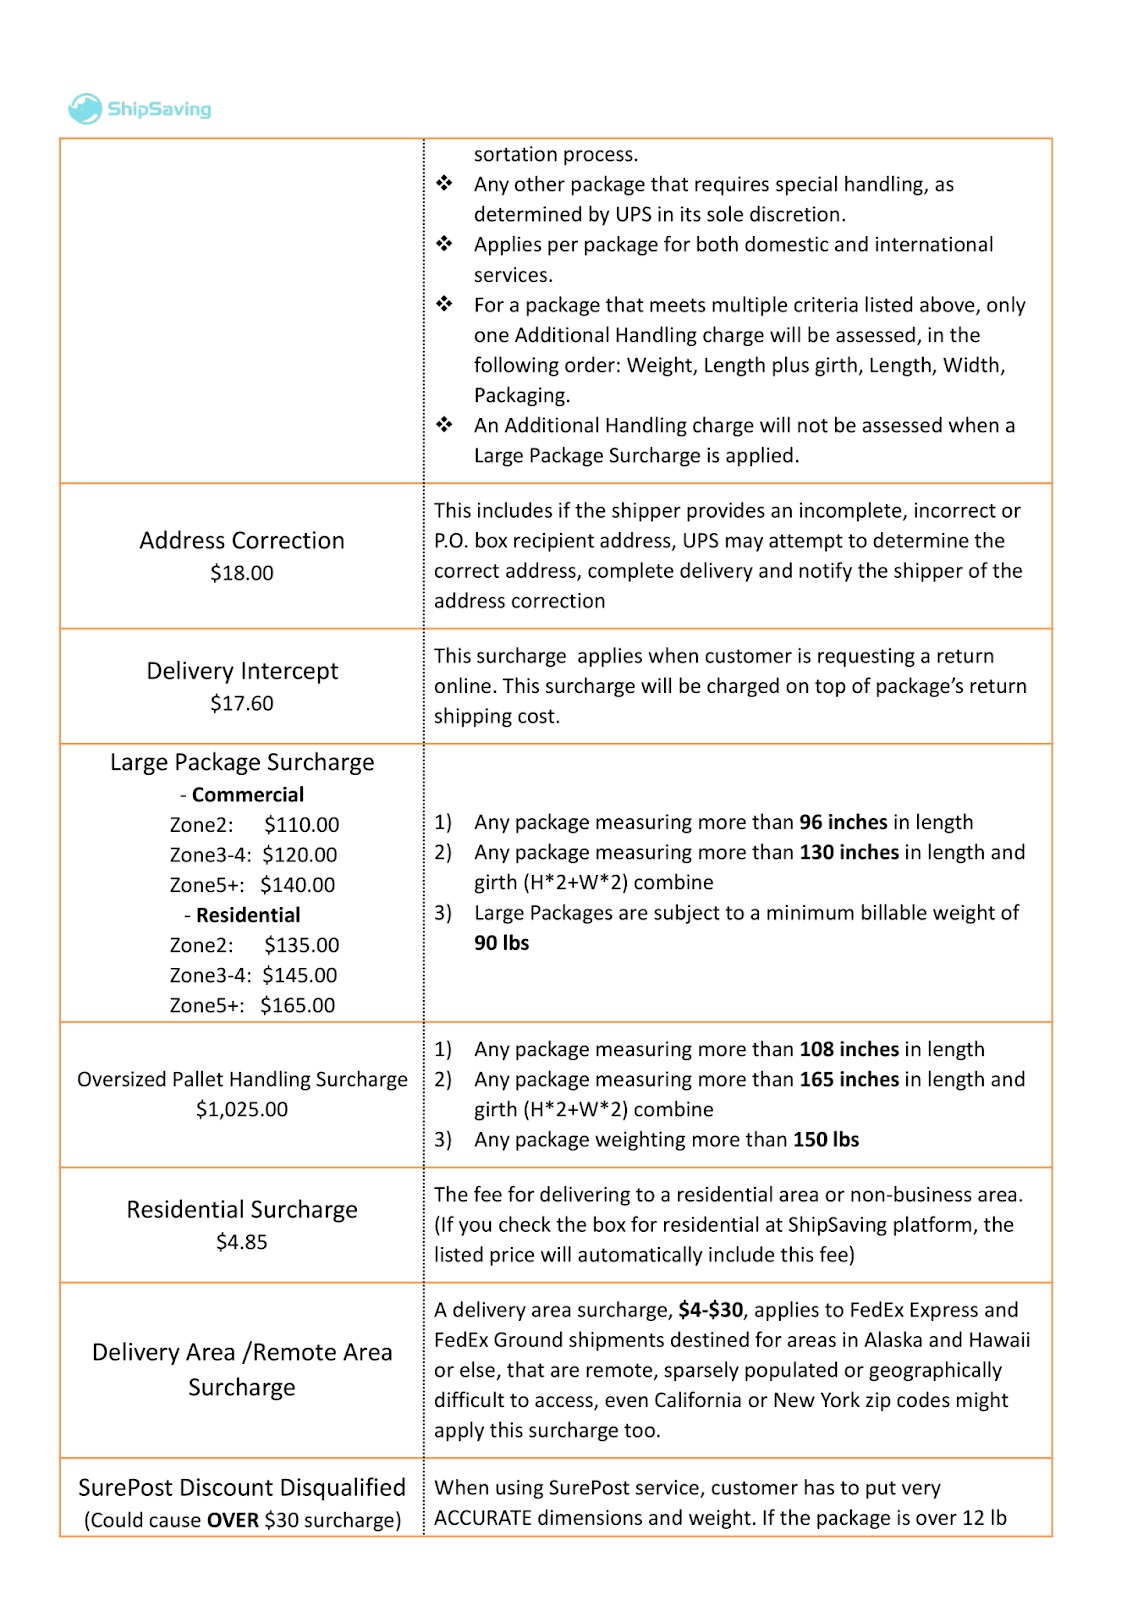
Start with the carriers' own price lists. Per the published 2026 rate tables (rates change yearly — always confirm against the current UPS and FedEx service guides):
| Declared value | UPS charge | FedEx charge |
|---|---|---|
| $0-$100 | Free | Free |
| $100.01-$300 | $5.10 flat | $4.95 flat |
| Over $300 | $1.70 per $100, counted from the first dollar, rounded up | $1.65 per $100 |
Two worked examples: $1,050 declared costs $18.70 at UPS (11 units x $1.70). $2,000 declared costs $34.00 at UPS and $33.00 at FedEx.
Before typing any number, check three caps — anything above them is money thrown away:
- FedEx Express (Overnight, 2Day, 3Day): $50,000 maximum declared value per shipment.
- FedEx Ground: $2,000 maximum. Declare more and the excess is void.
- UPS: $50,000 maximum ($70,000 with EMDV).
- Jewelry, watches, art, and other "items of extraordinary value" are capped at $1,000 flat by FedEx.
The first blunt line: if you ship high-value goods via FedEx Ground and keep paying declared value fees, every dollar above $2,000 is a donation.
Bill #2: declared value is not insurance
This is the most expensive misunderstanding in parcel shipping. UPS and FedEx state it plainly in their service guides: declared value is a liability limit, not insurance. FedEx's exact words: "WE DO NOT PROVIDE INSURANCE COVERAGE OF ANY KIND."
The difference is who carries the burden of proof:
| Carrier declared value | Third-party shipping insurance | |
|---|---|---|
| What it is | A purchased higher liability cap | An insurance contract |
| When something goes wrong | You must prove the carrier was at fault | You prove value and loss |
| Packaging questioned | Claim likely denied outright | Handled under policy terms |
| Rate (2026) | About 1.65-1.70% per $100 | About 0.75% per $100, lower at volume |
| Cap | $50,000 at UPS/FedEx Express | Per policy, can be higher |
In plain terms: declared value buys you the right to file a claim. On claim day, the carrier first audits your packaging, then audits whether the damage was its fault — both gates must pass before a dollar moves. A third-party insurer works from your invoice and damage photos. That is a claims process, not a fault trial.
In 2026 the U.S. Eighth Circuit Court of Appeals decided a case every shipper should read: a shipper sent a $250,000 watch via FedEx without declaring a higher value, the parcel was lost, and the court upheld FedEx's $100 liability limit. The court's logic was blunt — the carrier gave you the opportunity to purchase a higher limit, you didn't, the consequence is yours. Two lessons: no declaration means a $100 default; and declared value is a liability-cap game, so don't apply insurance logic to it.
Bill #3: where the break-even point actually sits
Cost analysis recognizes exactly one table. Same shipment, two ways to pay (2026 rates; third-party at $0.75 per $100 on the value above the carrier's free $100):
| Parcel value | UPS declared value | FedEx declared value | Third-party insurance |
|---|---|---|---|
| $100 | $0 | $0 | $0 |
| $300 | $5.10 | $4.95 | $1.50 |
| $1,000 | $17.00 | $16.50 | $6.75 |
| $2,000 | $34.00 | $33.00 | $14.25 |
| $5,000 | $85.00 | $82.50 | $36.75 |
| $10,000 | $170.00 | $165.00 | $74.25 |
The conclusion is cold and singular: at every value tier, third-party insurance costs less than half of carrier declared value. The break-even question — "above what value does real insurance win?" — has a one-line answer: anything above the free $100. Carrier declared value has no price advantage; its only value is convenience, one checkbox at label time.
Here is the counterintuitive part: declared value pricing is a linear function of value (1.7%), but loss probability is not a linear function of value. You pay $170 to cover $10,000 and $17 to cover $1,000, yet the first parcel is not ten times more likely to disappear. Carriers price on payout size, not on risk probability — the most expensive way to price insurance. That money is wasted on the pricing logic itself.
A quantified model: the California luxury reseller
Take a typical shipping profile for a pre-owned luxury consignment store in Los Angeles: 40 parcels a day, $450 average value, 300 working days a year. Previously, everything went out with full UPS declared value for convenience:
$450 rounds up to 5 units x $1.70 = $8.50 per parcel. Annual spend = $8.50 x 40 x 300 = $102,000.
Switching to third-party insurance ($0.75 per $100, covering only the value above the carrier's free $100): ($450 - $100) / 100 x $0.75 = $2.63 per parcel. Annual spend = $2.63 x 40 x 300 = $31,500.
Annual savings: $70,500 — enough to hire another packer with money to spare. The most common sentence I hear from sellers like this: "I thought ticking that box meant I bought insurance." "I thought" is the most expensive phrase in cost management.
The leverage points, ranked by savings
- Above $100 in value, stop using carrier declared value. Get a quote from a third-party shipping insurer; at volume the rate goes below $0.75 per $100.
- Check the $2,000 FedEx Ground cap before shipping high value. Over it? Switch service or go third-party — never pay void premiums.
- Parcels under $100 need nothing. The carrier's free $100 already covers them; extra spend is a donation.
- Declare actual value, never more. Every extra dollar is taxed at 1.7%, and claims still pay only actual loss.
- Photograph everything. Whichever option you buy, claim success lives or dies on packing photos and invoices. No evidence, no payout — whatever you paid.
The calculable conclusion
Pull your last 12 months of UPS/FedEx declared value spend and multiply by 0.45. That is roughly your annual premium with third-party shipping insurance. The difference is what "ticking the box for convenience" costs you.
The decision rule (tape it to the packing bench):
- Value at or under $100 → buy nothing; the free coverage already applies.
- Value over $100 → buy third-party shipping insurance; leave carrier declared value alone.
- FedEx Ground with value over $2,000 → change service or go third-party; never pay void premiums.
Money doesn't save itself. But once the arithmetic is clear, the savings are profit.
By Lao Zhou, Logistics Cost Analyst