Here's my verdict up front: an NNN lease isn't cheap. It just sells you the uncertainty.
If you're leasing warehouse space in the US, you will run into a document called a Triple Net Lease — NNN for short. It's the most common warehouse lease structure in American industrial real estate, and odds are you can't avoid it. So let's get triple net lease warehouse explained properly, once: what the three nets actually are, who really pays them, and three expensive lessons I've watched tenants learn the hard way.
Put simply, NNN works like this: the landlord collects a clean base rent, and the three nets — Tax, Insurance, Maintenance — get passed through to the tenant, usually pro rata by square footage in a multi-tenant building. Remember it as TIM: three letters, three bills.
Back in 2019, I walked a 60,000-square-foot building in Fontana with a client. The NNN quote's base rent looked nearly 30% cheaper than the gross lease next door. The client was ready to sign on the spot. I told him: hold on, let's run the TIM numbers first. He went quiet halfway through the math.
Triple Net Lease Warehouse Math: Who Pays the Three Nets
First, the rules. Under NNN, the tenant pays two things: base rent to the landlord, plus the actual cost of the three nets. The landlord hands you a budget number at the start of the year, collects it monthly, and reconciles at year-end — refund or balance due.
T is for Tax — property tax, paid to the county, with the landlord just passing it through. Here's where the trap sits: in places like California, when a property changes hands, the county reassesses it at the sale price, and the tax bill takes off.
The worst one I saw: in 2021, that Fontana client's landlord sold the whole building. The purchase price came in far above the last assessed value, the county reassessed, and the annual tax bill jumped from $180,000 to $260,000 — up 44%. My client ate over $80,000 of it, pro rata, with zero recourse, because the lease had no cap on tax increases. Two sides to this one: the landlord did nothing wrong selling the building, and the reassessment was perfectly legal. The mistake was signing a lease with no cap.
I is for Insurance — building insurance. Note the split: the landlord insures the building itself; you insure your goods, your equipment, and your liability. Neither side can skip it, and neither side should double-buy it.
In 2022, a Dallas tenant got burned twice on this. First, the overlap: he'd spent serious money on interior improvements and bought coverage for them — but the landlord's building policy already covered the same improvements. He burned over $20,000 a year in duplicate premiums, pure waste. Then, the gap: he skipped business interruption coverage, an ice storm knocked out power for three days, nothing shipped, and he collected nothing. My rule: the lease's insurance clause must spell out who covers what, and after signing, have a broker line up both policies side by side. Half a day of work can save tens of thousands.
M is for Maintenance — plus CAM, common area maintenance. Day-to-day repairs, the parking lot, landscaping, common lighting. The landlord reconciles actuals against your monthly prepayments at year-end: refund or balance due.
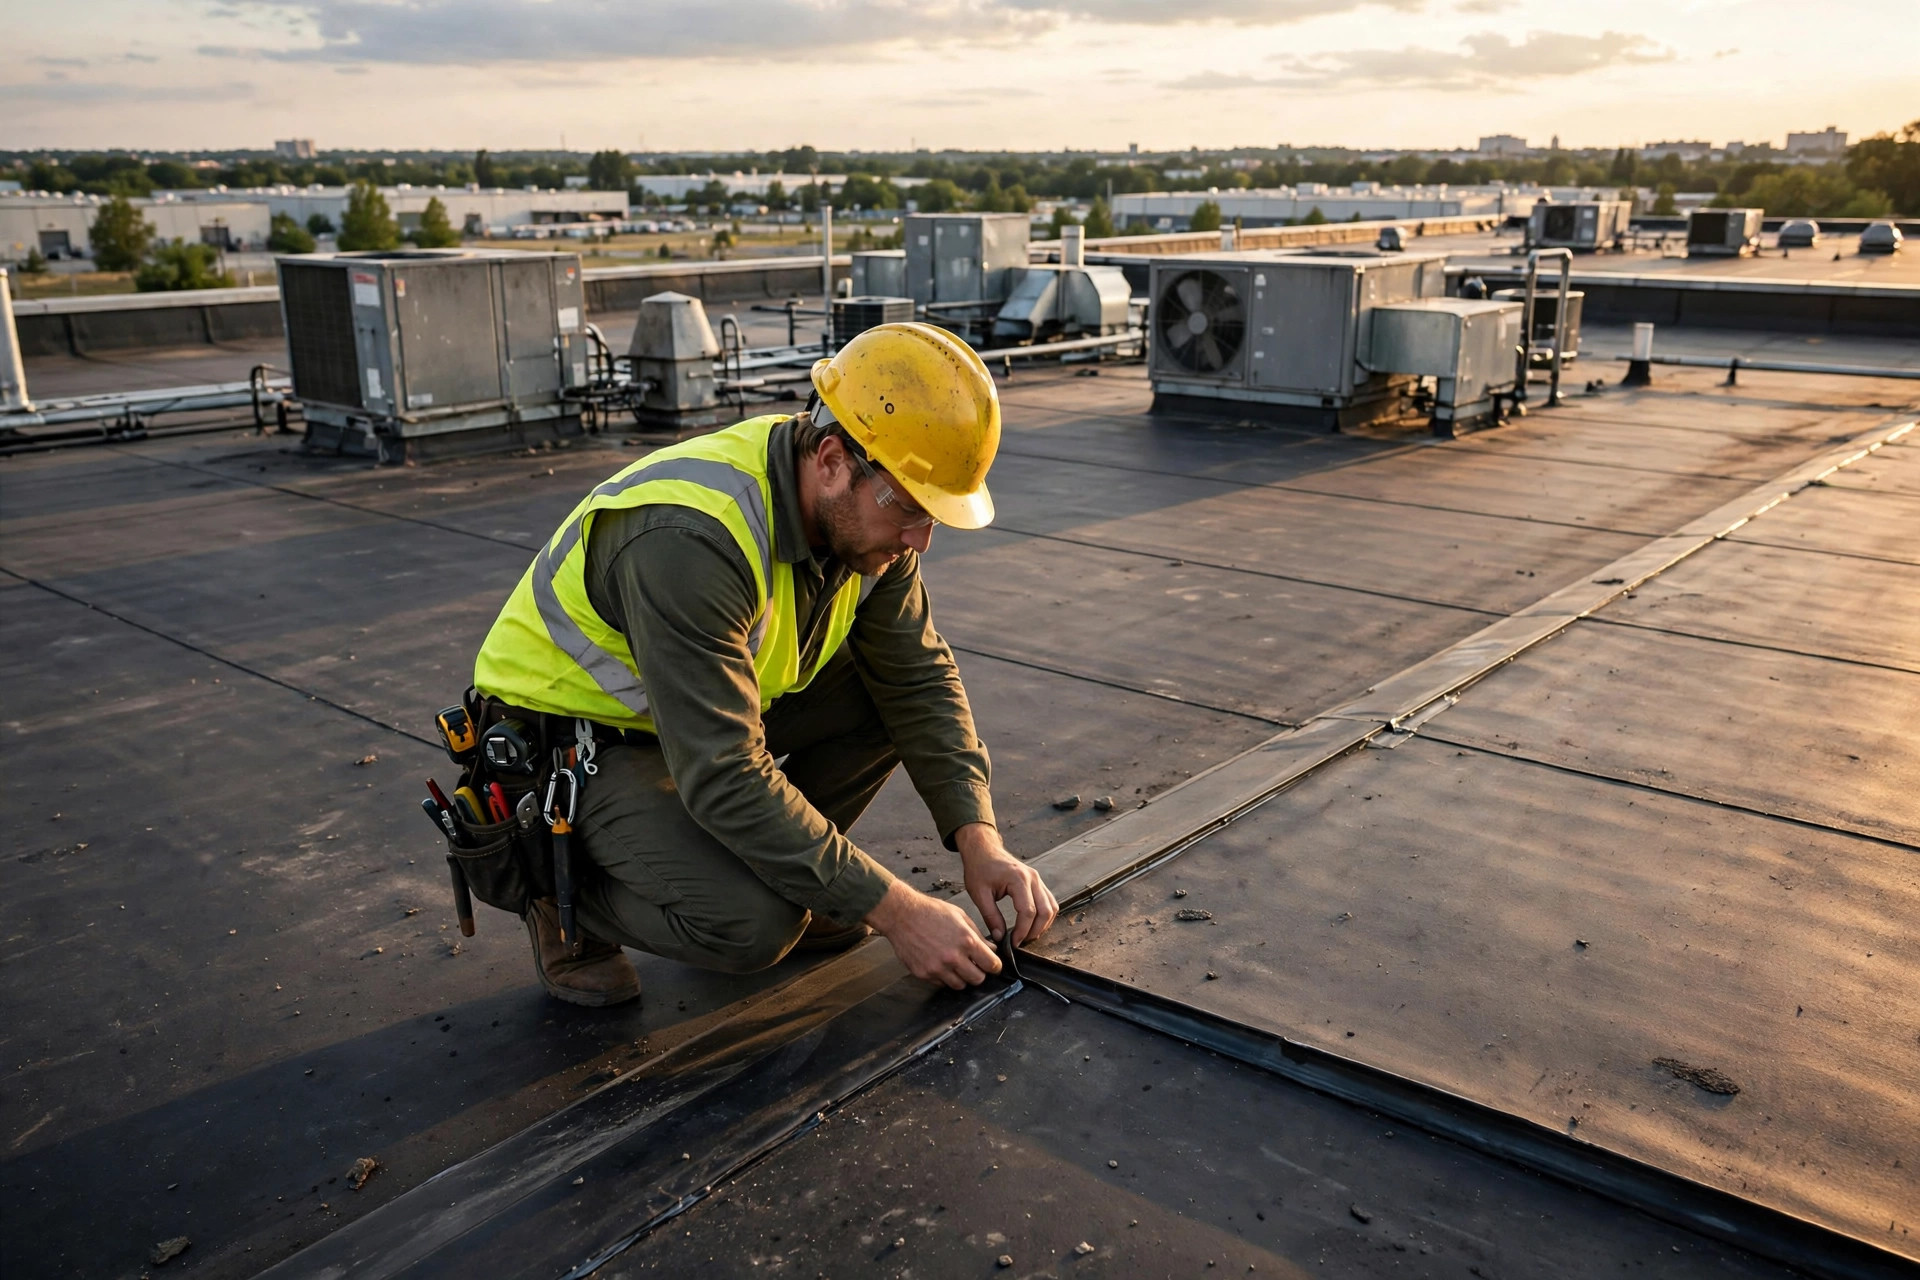
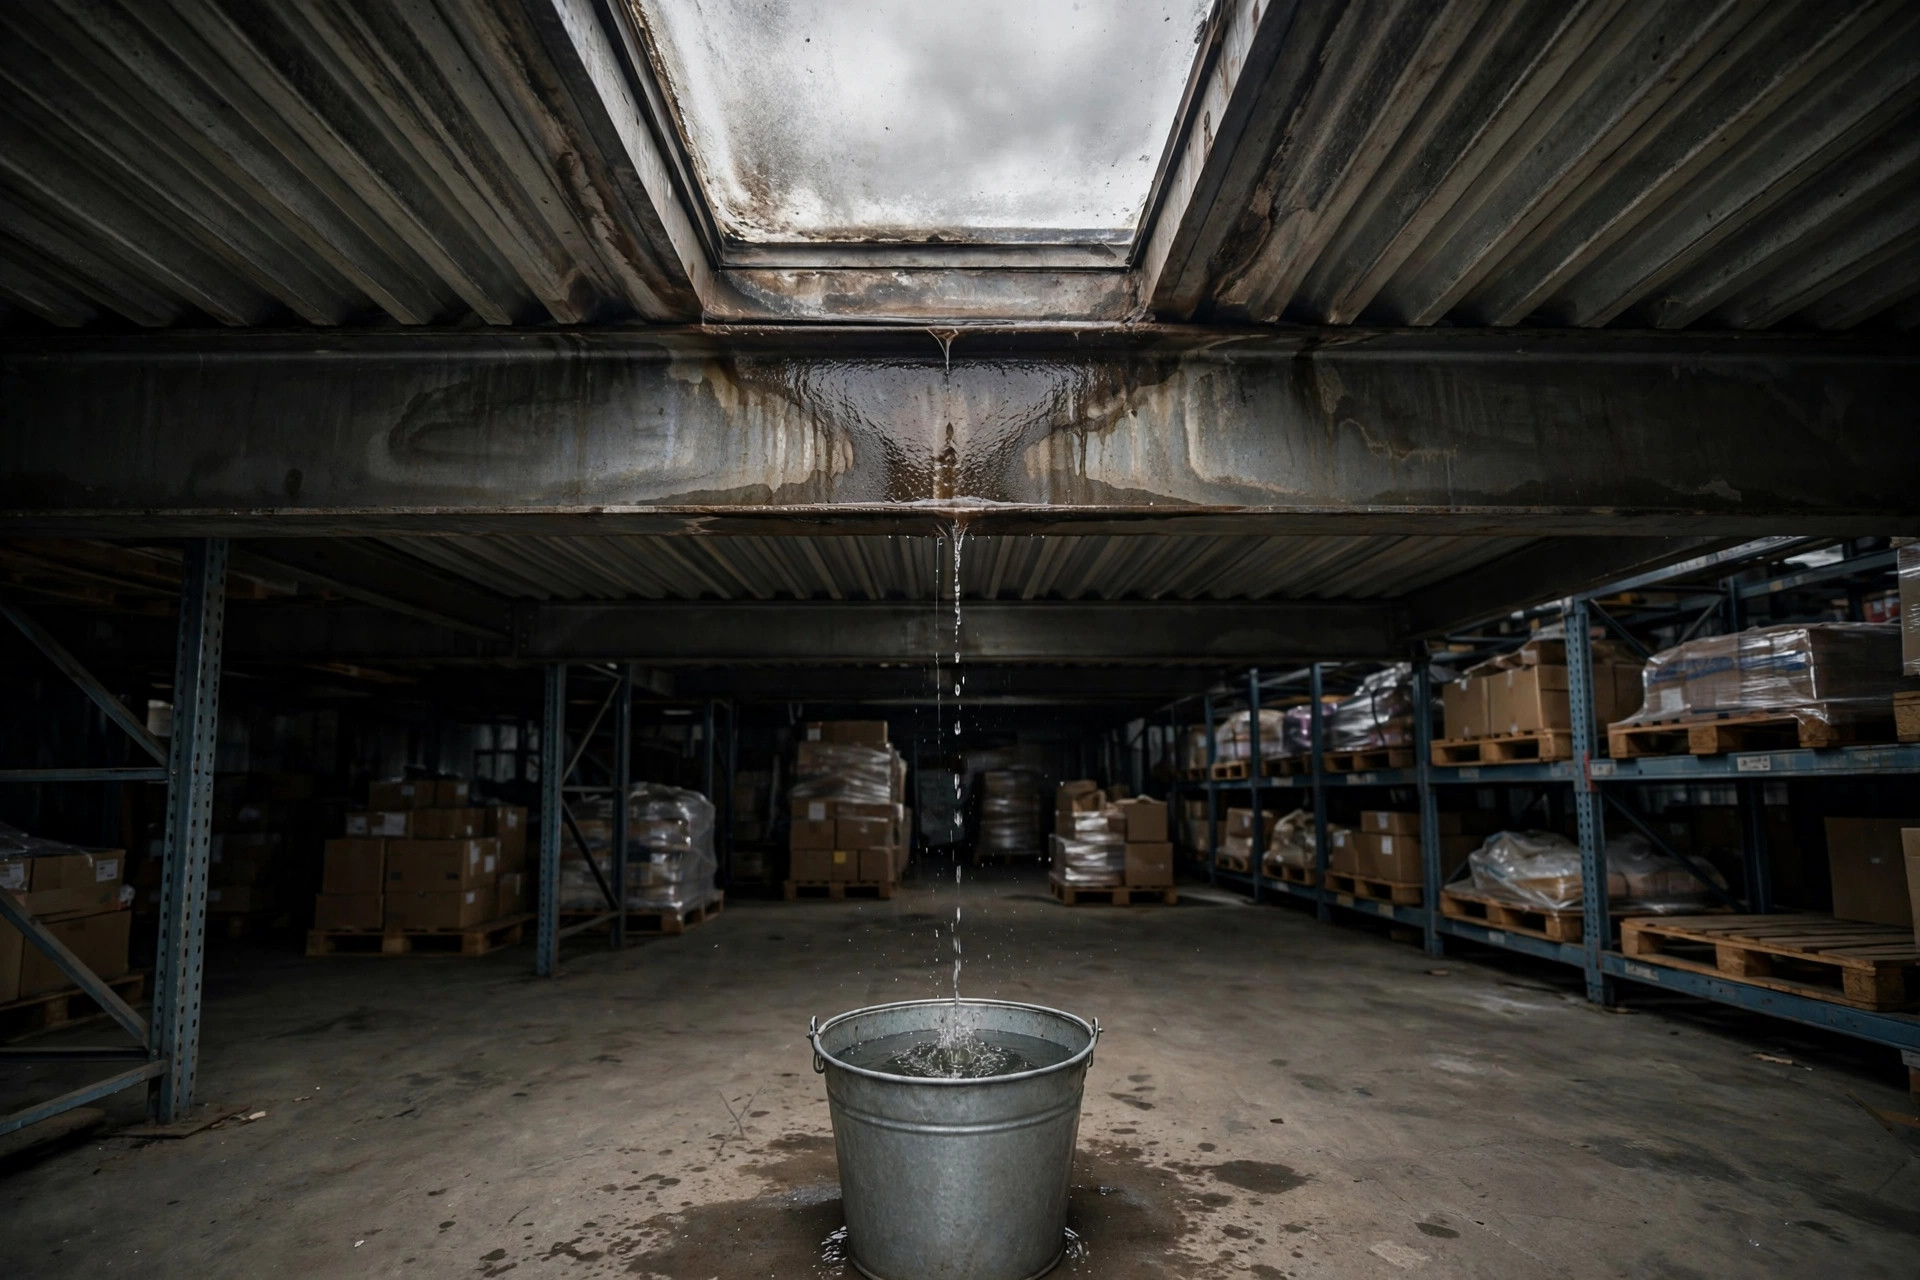
The biggest M fights are always the roof and the structure. In 2023, a Houston tenant's warehouse roof started leaking — a $120,000 repair quote. The lease said exactly one vague sentence: tenant responsible for maintenance. The landlord insisted that meant routine maintenance and therefore the tenant's bill; the tenant said it was a structural repair — a capital improvement — and therefore the landlord's. Four months of arguing, two rounds of water-damaged inventory, and they finally split it 50/50. Nobody won. The lesson: the line between maintenance and capital improvement has to be drawn in the lease before anything leaks, not after.
Five Clauses to Negotiate Before You Sign an NNN Lease
Seen the traps; here's the fix. Five non-negotiables I run through on every NNN lease review — skip one and don't sign.
Cap the tax increases. If you can't get a hard cap, at least negotiate a base year: you only share increases above the base-year amount. Post-sale reassessments are routine in California. Signing without a cap is walking in naked.
Audit rights on expenses. The landlord's year-end CAM reconciliation can't be take-it-or-leave-it. Write in your right to audit, plus a deadline — say, 120 days after year-end — after which the budgeted number stands if no statement arrives.
A written line between maintenance and capital improvement. Roof, structure, foundation: the landlord's responsibility, or a per-year cap on the tenant with the landlord covering the rest. A $120,000 roof bill should never be settled by shouting.
A hard split on insurance. Building policy: landlord. Property, liability, business interruption: tenant. Improvements: assigned to one side explicitly. Double-buying is waste; missing coverage is a disaster. I've seen both.
A reconciliation timetable. True-ups are the rule, but when the refund arrives — and what counts as late — has to be in writing. I've seen landlords drag reconciliation into the middle of the following year, which wrecks cash flow planning.
Triple Net vs. Gross: The Trade-off in One Table
Two sides to everything. Neither NNN nor gross is inherently better — it's about fit.
| NNN Triple Net | Gross (all-in) | |
|---|---|---|
| Base rent | Low — looks cheap | High — everything baked in |
| Tax/insurance/maintenance volatility | Tenant absorbs it | Landlord absorbs it (priced into rent) |
| Cost predictability | Low — moves every year | High — locked |
| Best for | Stable long-term tenants who can manage maintenance and audit CAM | Small teams, cash-flow-sensitive operators who don't want property headaches |
Run the illustrative math: a 100,000-square-foot building. NNN quotes $0.65 per square foot in base rent plus $0.45 in nets this year — $1.10 all-in. The gross quote next door: $1.12. NNN looks two cents cheaper. Then year two brings a higher tax bill, higher insurance, one roof repair — nets climb to $0.58, all-in $1.23, and suddenly you're paying 11 cents more. That's the truth about NNN: base rent is the down payment; the three nets are the monthly installments, and the installments go up.
Here's the counterintuitive part: the NNN quote with the lowest base rent is often the most expensive lease in the building — because a landlord confident in a low base rent is betting you can't do the TIM math. And those few "expensive" cents in a gross quote? That's the landlord selling you insurance against volatility. You sleep; he absorbs the swings.
So my verdict is simple: if someone on your team can read a CAM reconciliation and has the stomach to argue about who owns the roof, NNN can save you real money. If you'd rather focus on the business and never think about property management, those extra cents on a gross lease are worth it.
Next time a landlord slides an NNN lease across the table, don't look at the base rent first. Ask what each of the three nets cost last year. A landlord who can't answer those three numbers probably never intended for you to do the math.
By Lao Mi, Supply Chain Veteran (20 yrs)