Every warehouse operator has a version of this story. Mine goes like this: fall of 2021, a 3PL outside Columbus, Ohio runs its annual physical inventory and comes up short by well over a hundred thousand dollars in the high-value cage — mostly earbuds and small appliances. Three months of security footage, timecards, and awkward one-on-one interviews later, they pin it on two night-shift pickers. The merchandise is long gone, fenced or trashed. The owner's first call is to his insurance broker.
The answer comes back in two words: insufficient evidence.
I don't tell you this to scare you. Employee theft in warehousing is so ordinary that insurers built a whole product line around it. The uncomfortable part? Most operators either buy the wrong coverage — or buy the right coverage and still can't collect. I've watched both happen.
Why warehouses make such easy targets
Before the insurance talk, be honest about the exposure. A warehouse is a building full of small, valuable objects that aren't tracked in real time, staffed in shifts, with seasonal temp labor cycling through every peak season. Inventory records are always slightly wrong — that's normal — which means a smart thief hides inside the normal variance. Nobody notices two missing earbuds per shift. Over a year, that's a second salary.
The first line of defense isn't a policy. It's admitting the building is a target.
What crime insurance actually covers — read the exclusions twice
Commercial crime insurance, sometimes sold as a fidelity bond, centers on employee dishonesty coverage: losses caused directly by a dishonest act of an employee. Sounds tailor-made. The exclusions are where claims go to die.
Evidence is everything. A carrier doesn't pay on a hunch. A real claim file looks like this: a police report, a sworn proof of loss listing every SKU with quantity and cost, inventory and cycle-count records, the employee's timecards and task history, and something — footage, a witness, a confession — connecting a person to the loss. You assemble this before the adjuster shows up, not after.
The clause that kills most warehouse claims is the inventory shortage exclusion. If the loss can only be shown by an inventory computation — the system says X, the count says Y — and you can't prove specific goods were stolen by someone, the policy doesn't pay. Read that again, because this is exactly how most employee-theft cases present: the books don't reconcile, and nobody can say what walked out the door or when.
A few more things people learn too late. Per-occurrence deductibles apply, so a slow bleed of small thefts may never clear a single deductible. The discovery period matters: theft discovered months after someone quits is only covered inside the window your policy defines. And the standard exclusions list reads like a greatest-hits of warehouse reality: mysterious disappearance with no evidence of theft, normal shrinkage, bookkeeping errors — and losses caused by owners or partners, because the policy covers employees, not you.
Two practical moves. Schedule the high-value zone separately and set the limit against its peak inventory cost, not the average — losses always happen at the peak. And when something happens, the order is: police report, preserve the footage, freeze the count records — then call the insurer. Get the order wrong and the chain of evidence breaks before it starts.
One more timeline point. Crime policies set deadlines for notice and for the sworn proof of loss — the exact days are in your policy, but the principle is speed: open an internal case the day you spot the anomaly, file the police report and notify your broker within the week, and submit the proof of loss on the policy's schedule. Wait three months and the carrier's first question will be what you were doing all that time — while the evidence went stale. And revisit the limit every year: if the high-value cage's SKU mix or peak inventory changed and the limit didn't, you bought peace of mind you don't actually have.
Prevention: the unglamorous stuff that actually works
Insurance is the autopsy; this is the medicine.
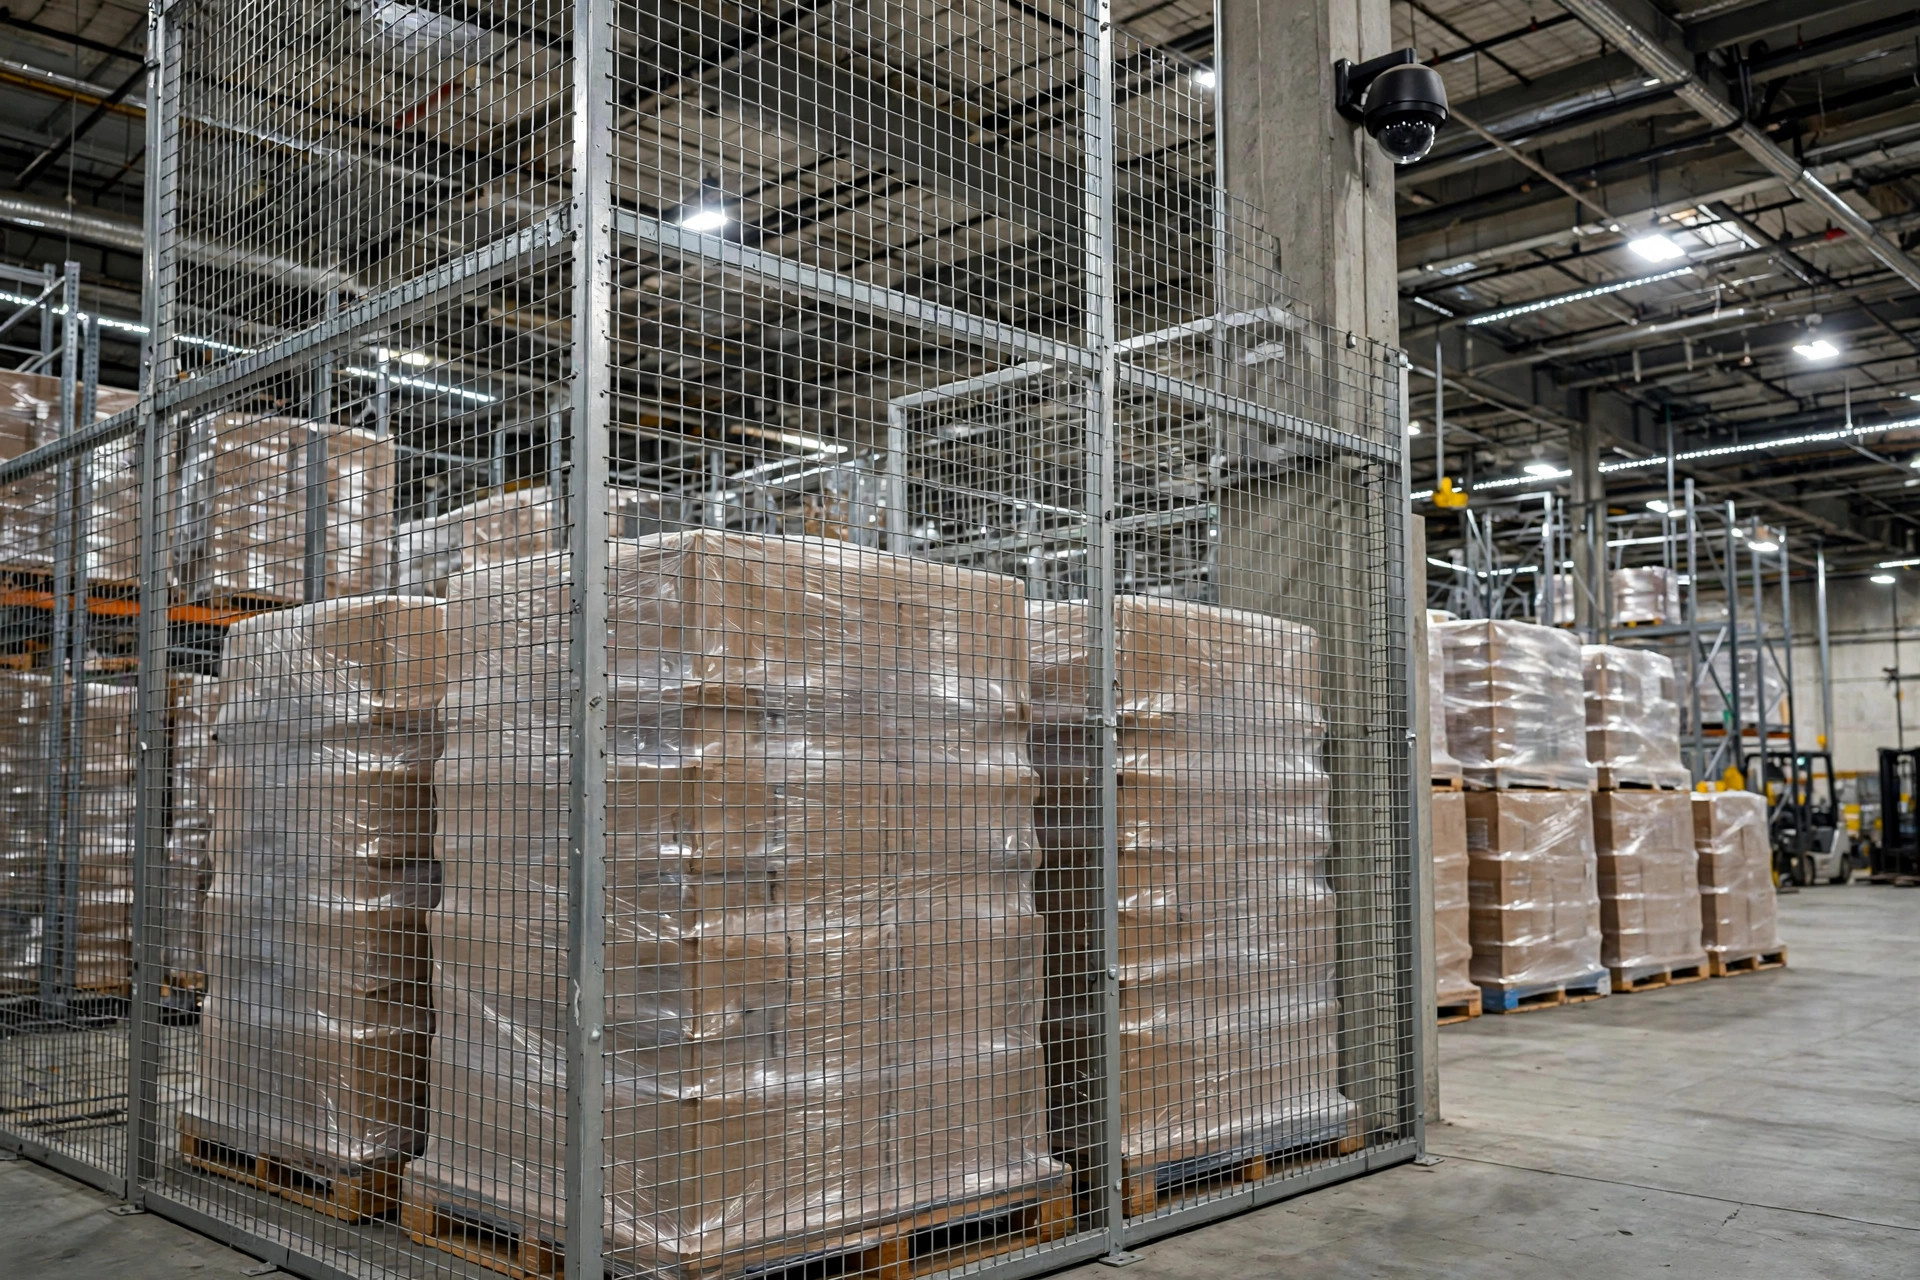
Cage the valuables. A fenced high-value area with badge access, an entry log, and a two-person rule on night shifts. If anyone can walk in unrecorded, someone will walk out with product. The cage pays for itself the first time it deters — or catches — someone.
Count the expensive SKUs weekly. Cycle counts on high-value items, variances investigated the same day, no "we'll look at it next week." And never let the person who keeps the books do the counting. Separation of duties isn't bureaucracy; it's the difference between a variance that gets investigated and one that gets quietly adjusted away.
Kill access on day zero. Badge and system access die the day someone leaves, not the following Monday. An uncomfortable share of theft happens in the two weeks before a resignation and in the grace period after a badge should have been collected. The exit checklist gets signed on the last day, before the final-paycheck conversation — not after.
Screen at hiring, but do it legally. Background checks in the US run through federal FCRA rules plus a patchwork of state ban-the-box laws. Get counsel before you build the screening policy, because a sloppy process creates the lawsuit that the theft never did.
Give people a way to report anonymously. A hotline or a dedicated inbox, with a modest reward. Loss-prevention surveys keep finding the same thing year after year: tips from coworkers uncover more internal fraud than audits or cameras do. Put it in the onboarding deck. Mention it in peak-season huddles. A channel nobody knows about is decoration.
None of this is exciting. None of it requires new software. It's fences, counts, checklists, and a phone number. Boring — right up until the year it saves you six figures.
The wall-poster version
- Does your high-value area have badge access with entry logs?
- Are expensive SKUs cycle-counted weekly, variances chased the same day?
- Are departing employees' badges and logins killed on their last day?
- Do your people actually know about the anonymous tip line?
- Does your employee-dishonesty limit cover a peak week of high-value inventory?
Five yeses: sleep well. Anything less: start at the top and work down. The next inventory is coming whether you're ready or not.