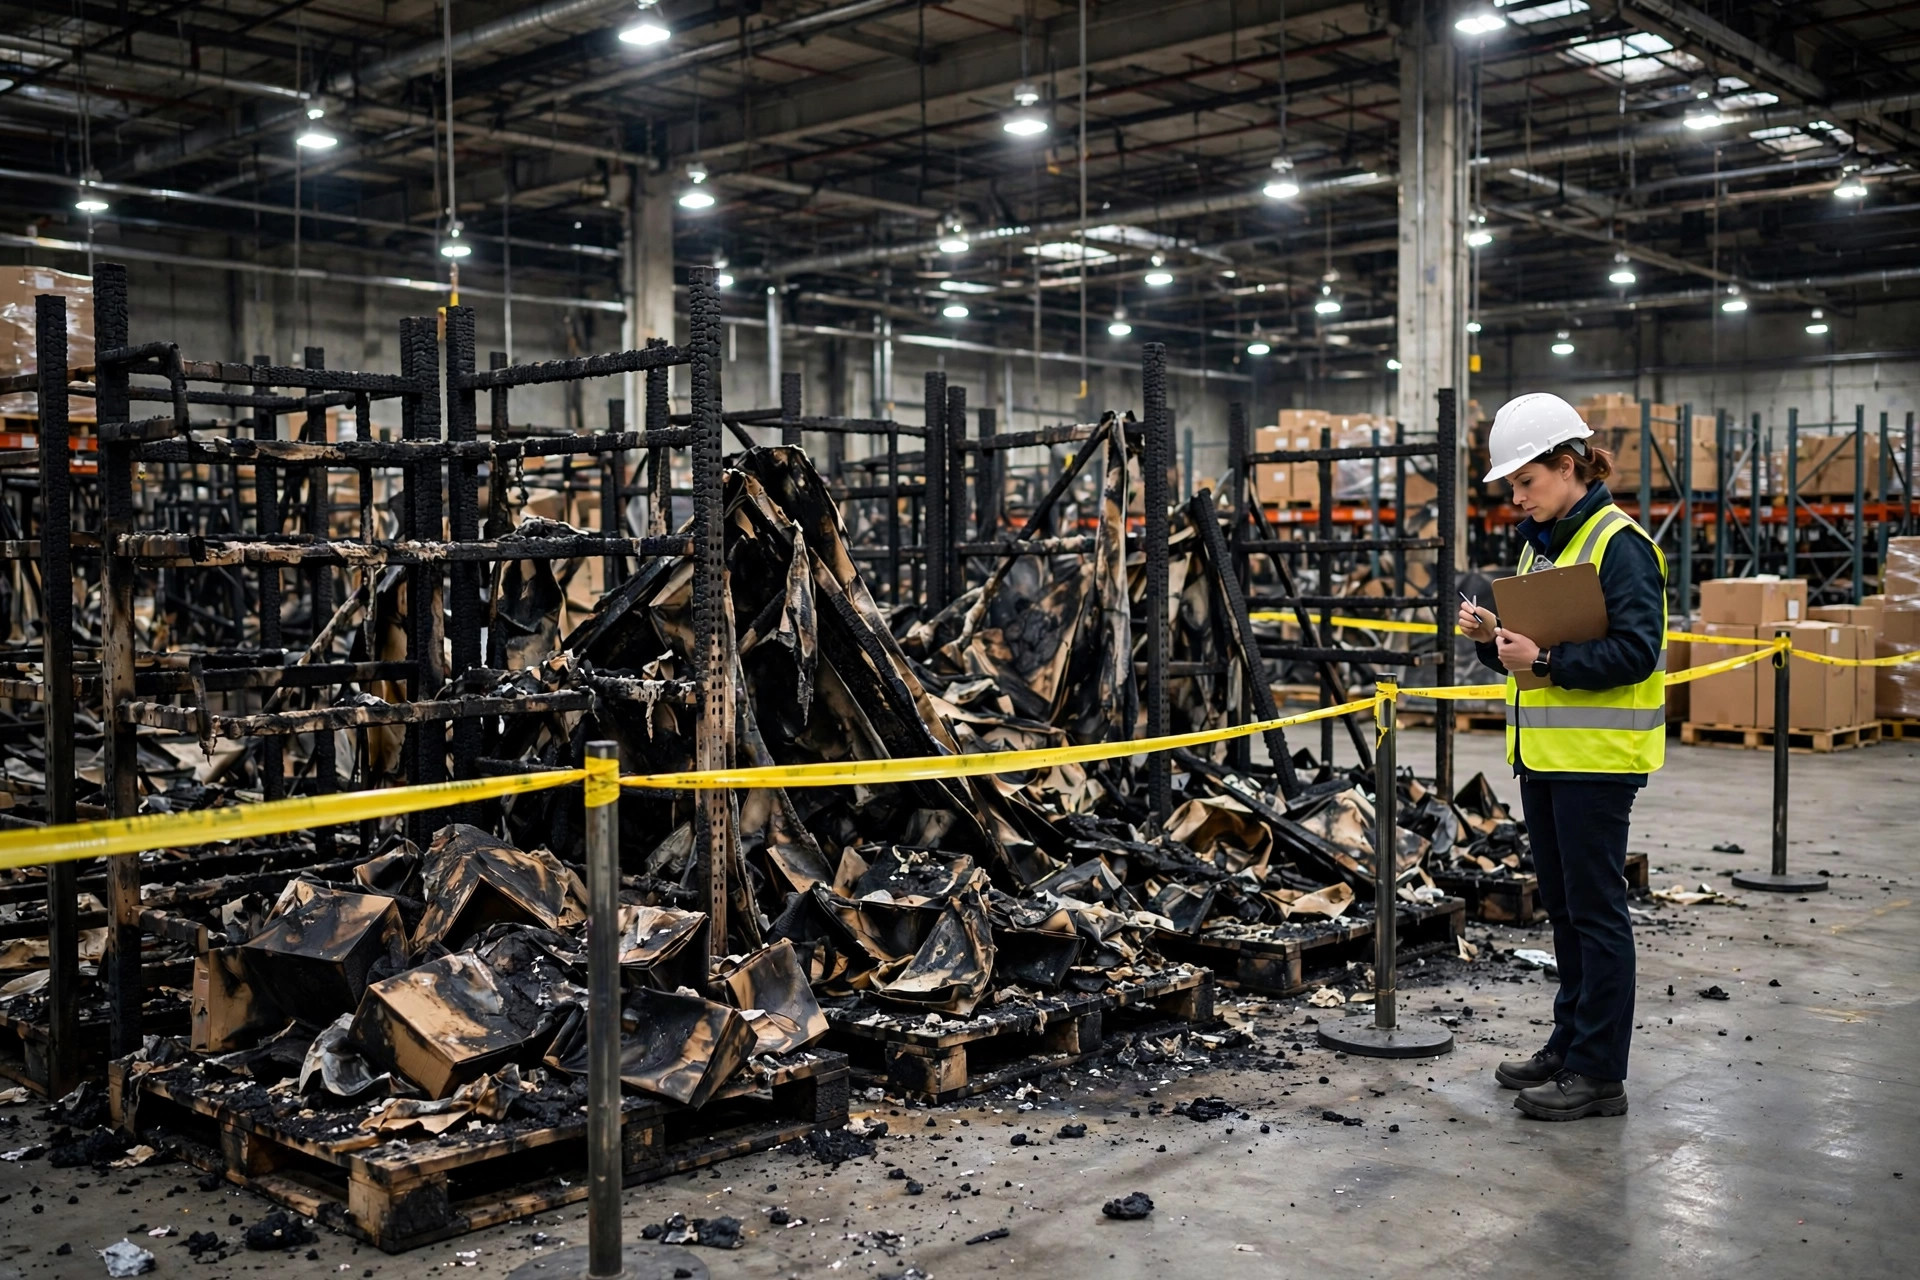
The math is ugly, so let's get it out of the way first. Your warehouse would cost $1 million to rebuild. Your policy carries an 80% coinsurance clause. You insured it for $600,000. An electrical fire destroys $200,000 worth of racking and inventory. You expect a $200,000 check. You get $150,000. Nobody denied your claim. The coinsurance clause simply took its cut — a 25% discount on money that was supposed to be yours.
I've heard some version of this story at least three times in recent years. Every renewal season, warehouse operators look at the premium, notice that higher limits cost more, and "optimize" the coverage down. The savings feel great — until the adjuster shows up and the policy pays back those savings with interest.
So let's open the hood on this clause. It lives in almost every commercial property policy, and almost nobody reads it until it's too late.
How the discount actually works
The logic of coinsurance is one sentence: the carrier prices your policy on the assumption that you insured the property close to its full value. Fall short of the agreed percentage and you become a "co-insurer" of your own loss — the claim gets split proportionally.
The formula: (limit you carry ÷ limit the clause requires) × your loss = what they pay. The required limit is the property's replacement cost at the time of loss, times the coinsurance percentage.
Walk the example through: $1 million replacement cost, 80% coinsurance, so the required limit is $800,000. You carry $600,000. $600,000 ÷ $800,000 = 0.75. Every claim pays out at 75 cents on the dollar. The $200,000 loss pays $150,000, and the deductible comes out of that on top.
The part that blindsides people: the penalty applies to every covered loss, no matter the size. A $50,000 partial loss — a scorched racking section, some melted cartons — takes the same 25% haircut. Plenty of owners assume underinsurance only matters in a total-loss catastrophe. Wrong. Small claims get discounted just the same.
And it gets nastier: 90% coinsurance is showing up in more policies now. Same $1 million warehouse, required limit jumps to $900,000. You carry $600,000, the ratio drops to two-thirds, and the same fire pays out at 67%. Same loss, a worse check — because of one number in the fine print.
Which "value" your limit has to track
This is where warehouse operators stumble most often. Three traps.
First, the valuation method. Commercial policies settle on one of two bases: replacement cost — what it costs to replace with new, like kind and quality, with no depreciation deducted — or actual cash value, which is replacement cost minus depreciation. A ten-year-old racking system might cost $80,000 to replace new but settle at $20,000 on an actual-cash-value basis after depreciation. My verdict for warehouses: replacement cost is the only sane choice. With the amount of racking, conveyors, and material handling equipment in a facility, actual cash value coverage is a self-inflicted wound.
Second, the sneakier one: the denominator in the coinsurance formula is the value at the time of loss, not the value when you bought the policy. Say you set your limit five years ago when the rebuild cost was $800,000 — at 80% coinsurance you needed $640,000, you carried $650,000, you were fine. But construction costs have moved. If the rebuild cost is $1 million today, your required limit is $800,000 and your unchanged $650,000 now pays out at 81 cents on the dollar. The policy never changed. The market quietly pushed you into the penalty zone. That's why limits need a fresh look every single year.
Third, inventory swings. Warehouse inventory value fluctuates — peak-season stock can be two or three times the off-season level. Buildings, equipment, and stock are three separate calculations; don't blend them. Plenty of operators fully insure the building and insure inventory at its sleepy off-season value, then take a hit in October when the building is full.
How much coverage is actually enough
My take: if you can afford 100%, don't flirt with the 80% line. The coinsurance percentage is just the minimum that keeps the penalty away — it's not the smart target. Market values move every year; riding the minimum means gambling every year that your valuation didn't drift. Insuring to 100% of replacement cost buys you a cushion.
The practical playbook: first, get a professional replacement-cost appraisal — not the book value from accounting, not the price you paid for the building. Replacement cost means rebuilding right now, on the same site, with comparable materials. Second, appraise and schedule buildings, equipment, and inventory separately. Third, re-appraise before every renewal, and eyeball inventory limits before peak season.
One more move most people never hear about: the agreed value endorsement. You and the carrier agree on the property's value up front and write it into the policy — and the coinsurance clause goes dormant. No valuation argument at claim time. Carriers will ask for a signed statement of values in exchange, which is a fair trade.
And the premium objection? Moving from 80% to 100% of value doesn't raise the premium by 25%. The marginal premium per dollar of coverage declines as the limit rises. Compare that small extra premium to a claim that could pay 25 to 33% short. Do the math.
Your checklist for tomorrow morning
- Pull your policy and find the coinsurance percentage — 80, 90, or 100. Know the rules of your game.
- Confirm whether your policy settles on replacement cost or actual cash value. If it's ACV, fix that first.
- When was your last replacement-cost appraisal? If it's older than a year, schedule one.
- Check buildings, equipment, and inventory separately: does each limit clear (coinsurance percentage × current replacement value)? Top up where it falls short.
- Ask your broker about an agreed value endorsement that suspends the coinsurance clause.
- Put "re-appraise before renewal" on your own annual calendar, next to the fire inspection and the physical inventory.
Coverage always feels expensive when you buy it and inadequate when you need it. The coinsurance clause won't send you a reminder — it just quietly takes its share on the worst day of your year. Don't wait for that day.