It is the fourth quarter of 2026, and most companies are closing out their 2027 budget cycles. Supply chain and warehousing IT leaders are answering the same question: where should next year's AI budget actually go? Rather than rely on instinct, it is worth starting from two published industry surveys, then reasoning from the data toward an answer.
What Two Surveys Say About the 2027 Warehouse AI Budget Climate
According to the "2025 MHI Annual Industry Report," published jointly by MHI and Deloitte in March 2025 and based on a survey of supply chain practitioners, 28% of respondents reported they were already using AI in supply chain operations, with another 54% planning to do so within five years. That puts the five-year cumulative adoption figure at roughly 82% by 2029. The three highest-intent AI application areas were inventory and network optimization (92%), cloud computing and storage (91%), and sensors and automatic identification (88%). Separately, 45% of respondents planned to purchase automation equipment such as AMRs, automated storage and retrieval systems, and robotics within the next three years, and the share of organizations planning to increase re-skilling and re-training efforts rose from 25% in 2024 to 38% in 2025.
A second data point comes from Modern Materials Handling's "2026 Outlook Survey." It found that 28% of respondents expected company spending on materials handling solutions to increase in 2026, by an average of 27%. Among companies still moving forward with investments, 59% were spending on technology information systems such as WMS, versus 41% on automation technologies. Looking two to three years out, 42% expected spending to increase, up from 35% the previous year.
Taken together, the picture is one of cautious budgets but clear direction: most firms are holding steady or waiting, yet the money that is being spent is tilting decisively toward software — WMS, WCS, data platforms — and automation equipment. That is the right starting point for asking where next year's warehouse AI budgets will flow: the question is no longer whether to fund AI, but which projects get funded first.
Three Project Types Likely to Absorb 2027 Warehouse AI Budgets
The attribution logic runs like this: 2023–2025 was the pilot era for warehouse AI, dominated by proof-of-concept projects. The 2027 budget cycle marks a shift toward replication and monetization. Against that backdrop, and consistent with the two surveys above, capital is most likely to flow into three categories.
The first is scaled replication of projects with proven ROI — AI vision inspection, forecast-driven replenishment. The MHI survey ranks inventory and network optimization first in AI intent at 92%. What these projects share is that they have already been proven in one or two facilities, their impact is measurable, and the marginal cost of rolling them out to additional sites is low. For 2027 budgets, the posture toward them will be expansion rather than another round of experimentation.
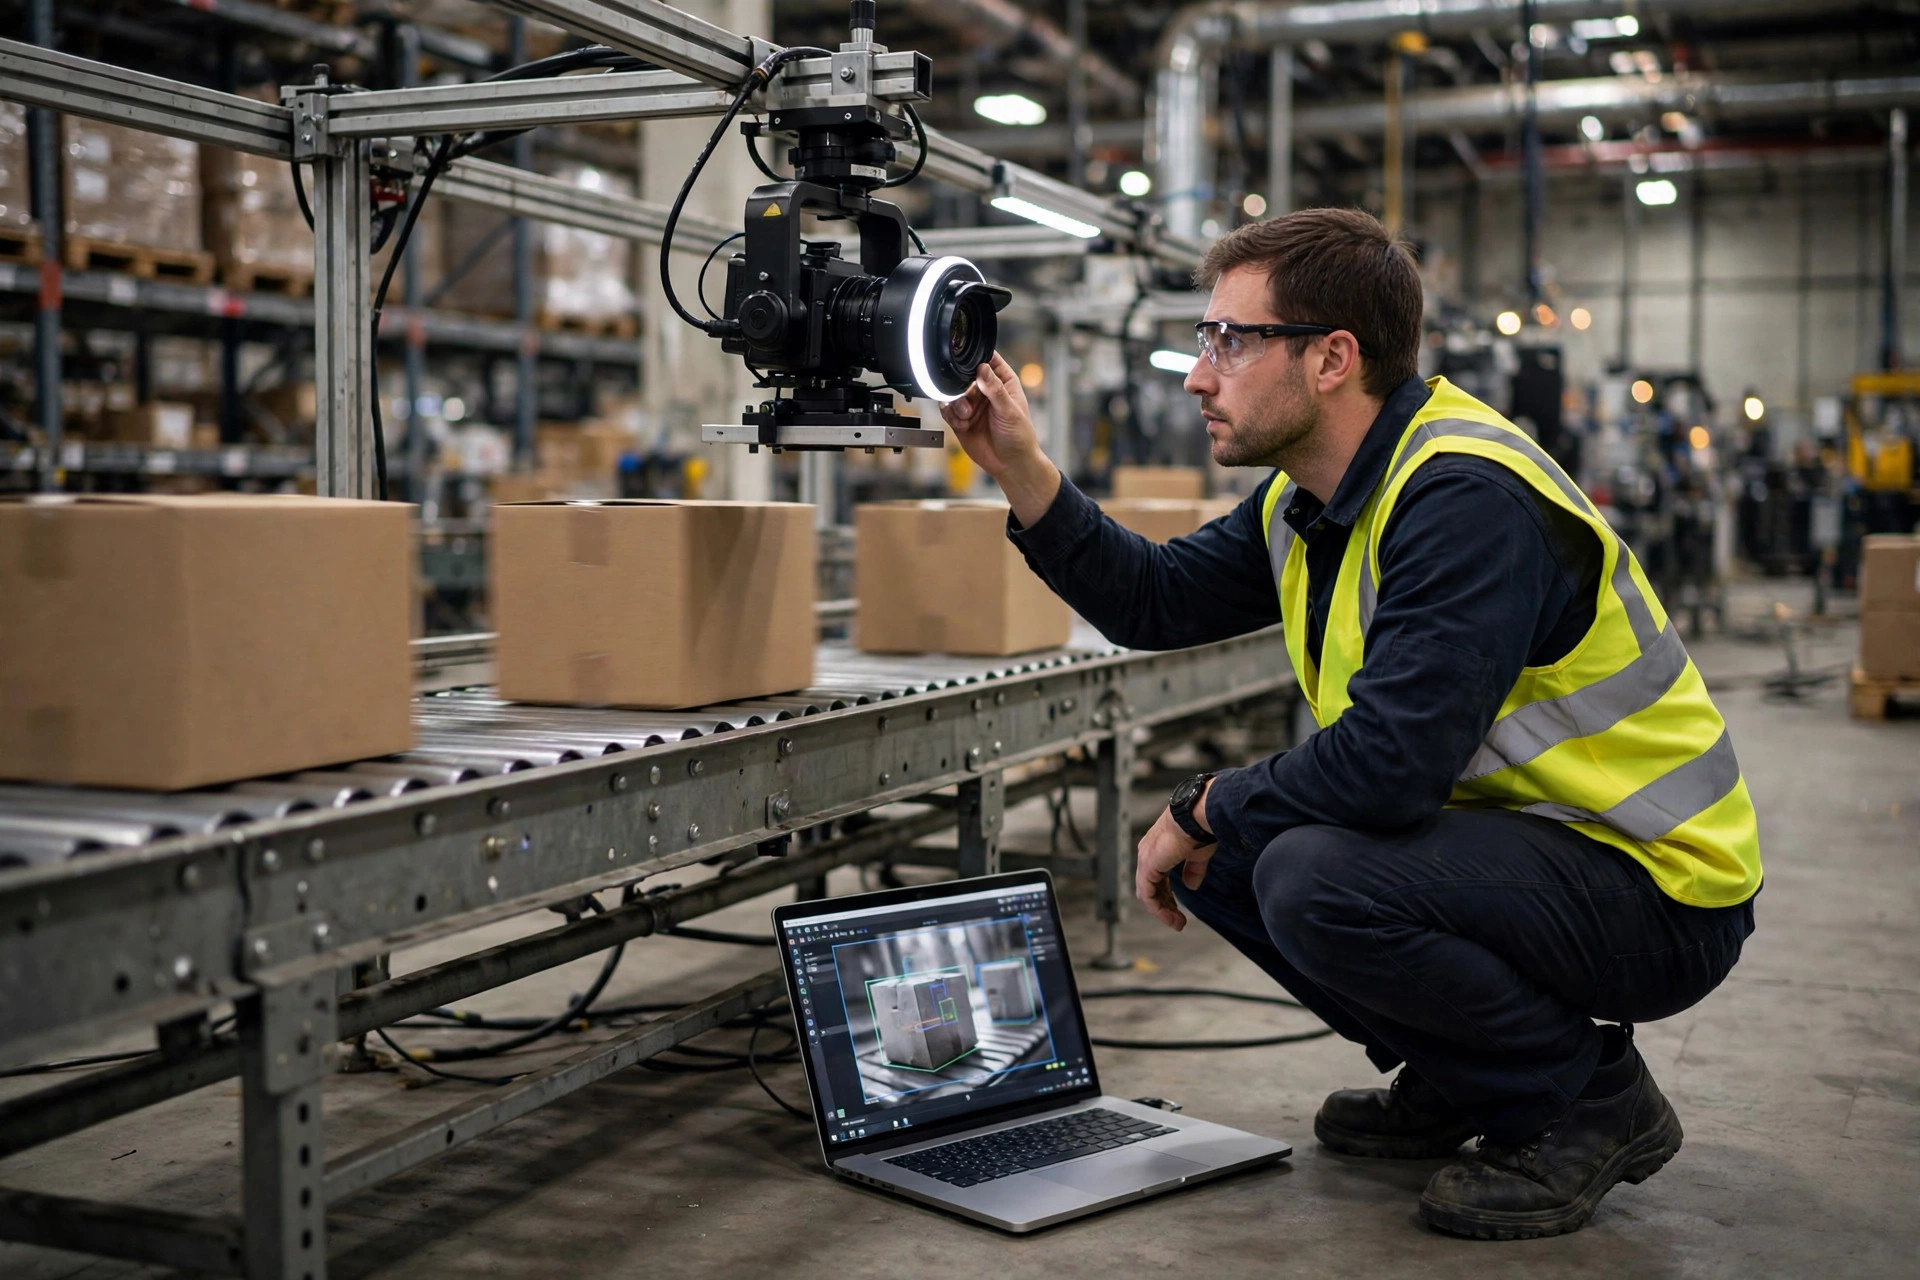
The second category is process automation with immediate, calculable payback — AMR fleet scheduling optimization, intelligent recognition of inbound documentation. These projects make no grand claims; their math is direct. Saved labor hours, reduced empty travel miles, and faster document processing all convert into dollars within a twelve-month horizon. The MMH survey's finding of rising investment intent around "lowering labor requirements" points in the same direction. One clarification is in order: this is the combination of automation plus algorithmic optimization, not equipment purchases alone. The hardware has its own capital budget line; the AI budget pays for making the equipment smarter.
The third category is data infrastructure: master data governance, data lakes, and cross-system data observability. It is the least glamorous and the easiest to cut, yet it may become the most rigid line item in 2027 AI budgets. The evidence comes from a striking admission in the MHI report: many companies have already invested heavily in advanced data collection systems and point solutions, yet still struggle to analyze the data, place it in a larger context, and extract genuinely usable insight. The report's recommendations lead with "unified, accurate data." Without that foundation, replicating the first two categories will stall.
Two Observations Worth Noting
Observation one, from the MHI/Deloitte survey published in March 2025 (a U.S. supply chain practitioner sample): 45% of firms planned to buy AMRs, AS/RS, and robotics within three years. That is a "pilot to procurement" signal. If 2023–2024 warehouse AI lived mostly in software proofs of concept, then by the 2027 budget cycle, equipment-side money is catching up. The practical implication is that AI budget planning cannot look at the software line in isolation; it has to move in step with automation capex. Inspection cameras for vision quality checks, scheduling algorithms for AMR fleets, digital twins for AS/RS — software and hardware are one ledger.
Observation two, from the Modern Materials Handling survey in early 2026: among companies still investing, 59% of spending went to information systems like WMS, well above the 41% going to automation technology. Software investment is running ahead of hardware, and the ordering is telling — money is flowing first toward the invisible data work: system upgrades, interface integration, KPI data capture. The same survey flags an emerging pattern of "capturing data for key performance indicators with automation, with artificial intelligence likely to play a role in gaining value from the data." In other words, the data-infrastructure spend is already happening; many companies simply have not given it its own budget line yet. In 2027, it will be formally on the table.
A Reference Framework for Allocating the 2027 AI Budget
Based on the reasoning above, a workable starting framework allocates roughly 50% to scaling proven projects (lowest risk, most certain return), 30% to payback-driven process automation (screened on a twelve-month payback threshold), and 20% to data infrastructure (master data governance, data lakes, interface standardization).
To be explicit: this 5:3:2 split is a heuristic framework, not a statistical finding from any published survey. Real-world ratios should follow each company's digital baseline. Firms with poor WMS data quality should push the data-infrastructure share higher; firms that have already proven two or more AI use cases can afford to weight replication more heavily. The framework's value is as a starting point for discussion, not as a standard answer.
A Counterintuitive Call
Judged purely on where the money flows, a counterintuitive conclusion emerges: the biggest winners of next year's warehouse AI budget cycle may not be algorithm vendors, but the service providers that help warehouses get their data in order.
The logic chain holds together. The MHI survey shows supply chain AI adoption climbing from 28% toward 82% on a five-year horizon — the money is coming in. But the same report concedes that the binding constraint is not a shortage of algorithms; it is fragmented, dirty, disconnected data. Algorithm vendors sell capability; data governance, systems integration, and master data service providers sell the precondition for AI to work at all. In the language of budget approvals, the precondition often clears committees more easily than the capability, because one addresses pain already felt while the other promises gains still to come.
This call has a time boundary: it holds for the 2027 window, the transition from pilots to replication. If by 2028–2029 most firms have completed their data-infrastructure catch-up, budget gravity will naturally swing back toward algorithms and agents.
Three Questions to Revisit at the End of 2027
Rather than conclude, three questions are worth revisiting at year-end 2027. First, will the MHI survey's 82% five-year adoption figure be met early, or discounted by reality? Second, can the industry agree on a credible way to calculate ROI for data-infrastructure spending? Third, once AMR scheduling and replenishment decisions are handed to algorithms, what exactly are the people in the warehouse managing?
The answers will determine where 2028 budgets go. And for 2027, the data suggests the money will flow first to what can be replicated, what can be counted — and what makes the data clean enough for everything else to work.
By Dr. Chen, Supply Chain Researcher