Bottom line first: in a Mexico IMMEX maquiladora warehouse program, your warehouse size does not decide whether you survive an audit. Your ledger does. If, on the day customs walks in, you cannot explain where every temporarily imported lot came from and where it went, the tax savings you banked will come back as back taxes, penalties, and possibly a lost authorization. I have seen this failure three times, and all three times the warehouse itself was well run. The books were not.
That is the first thing to understand about IMMEX. A regular warehouse tracks whether goods are present and sufficient. An IMMEX warehouse tracks identity. Inside the same building, temporarily imported materials and domestic materials can look identical, but legally they are different species. One entered temporarily for processing and re-export, with deferred tax treatment. The other already belongs to the domestic market. Mix the identities and the whole ledger is contaminated.
I worked on a project in Monterrey with a wire harness manufacturer. Inventory accuracy was good, cycle counts were clean, and nobody had ever flagged a warehouse problem. Then customs sampled lots during an inspection and found temporarily imported connectors stored in the same location as domestically purchased connectors of the same part number, with picking documents that did not distinguish the source. The goods were right. The records were a mess. Explaining and reconstructing the paper trail took months, and the plant nearly ran out of material. The lesson I still teach from that project: in an IMMEX warehouse, the first receiving step is not unloading. It is assigning identity.
Do you even qualify for IMMEX, and is it worth it
Before designing anything, check the door. Commonly published guidance puts the export threshold at around $500,000 per year or exports equal to 10% of sales, subject to the latest criteria from Mexico's Ministry of Economy. Treat that number as a filter, not a target. It forces an honest calculation: maintaining an IMMEX authorization costs real money every year, in systems, dedicated reconciliation staff, annual reporting, and audit response time. If your export volume is small, the tax saved may not even cover the compliance cost, and you would be better off importing normally.
There is also a counterintuitive point that surprises first-timers. Under IMMEX, the most expensive thing is not the tax. It is losing control. The widely cited 16% value-added tax can be deferred or exempted under compliant operations, subject to current law, but a violation finding can wipe out years of savings in one stroke through back taxes, penalties, and suspension. IMMEX is not a tax-saving trick. It is a deal: you trade rigorous compliance for a cost advantage. How much you are willing to pay for that compliance decides whether the program fits you at all.
Keep temporary and domestic stock physically apart in an IMMEX warehouse
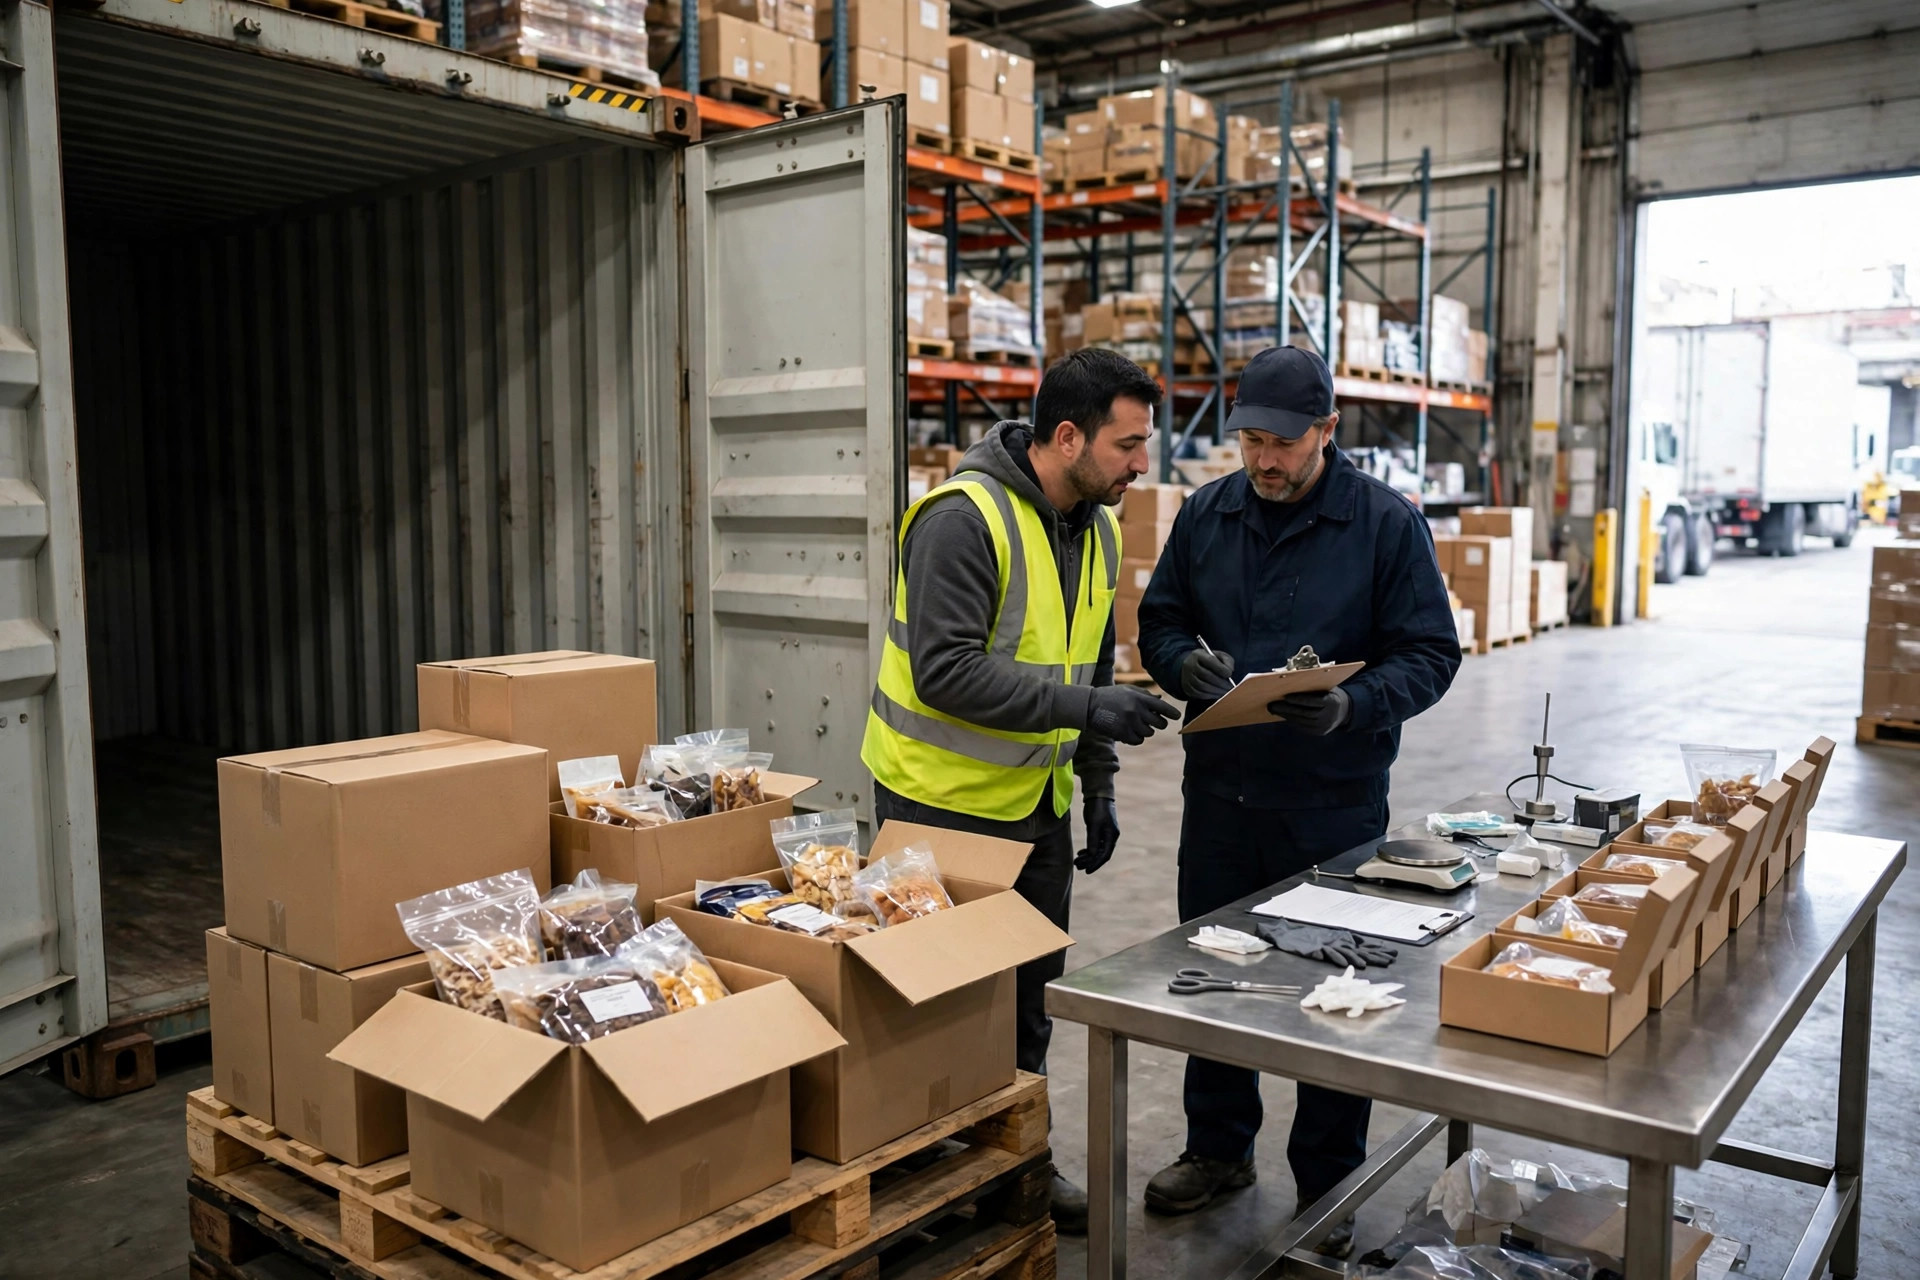
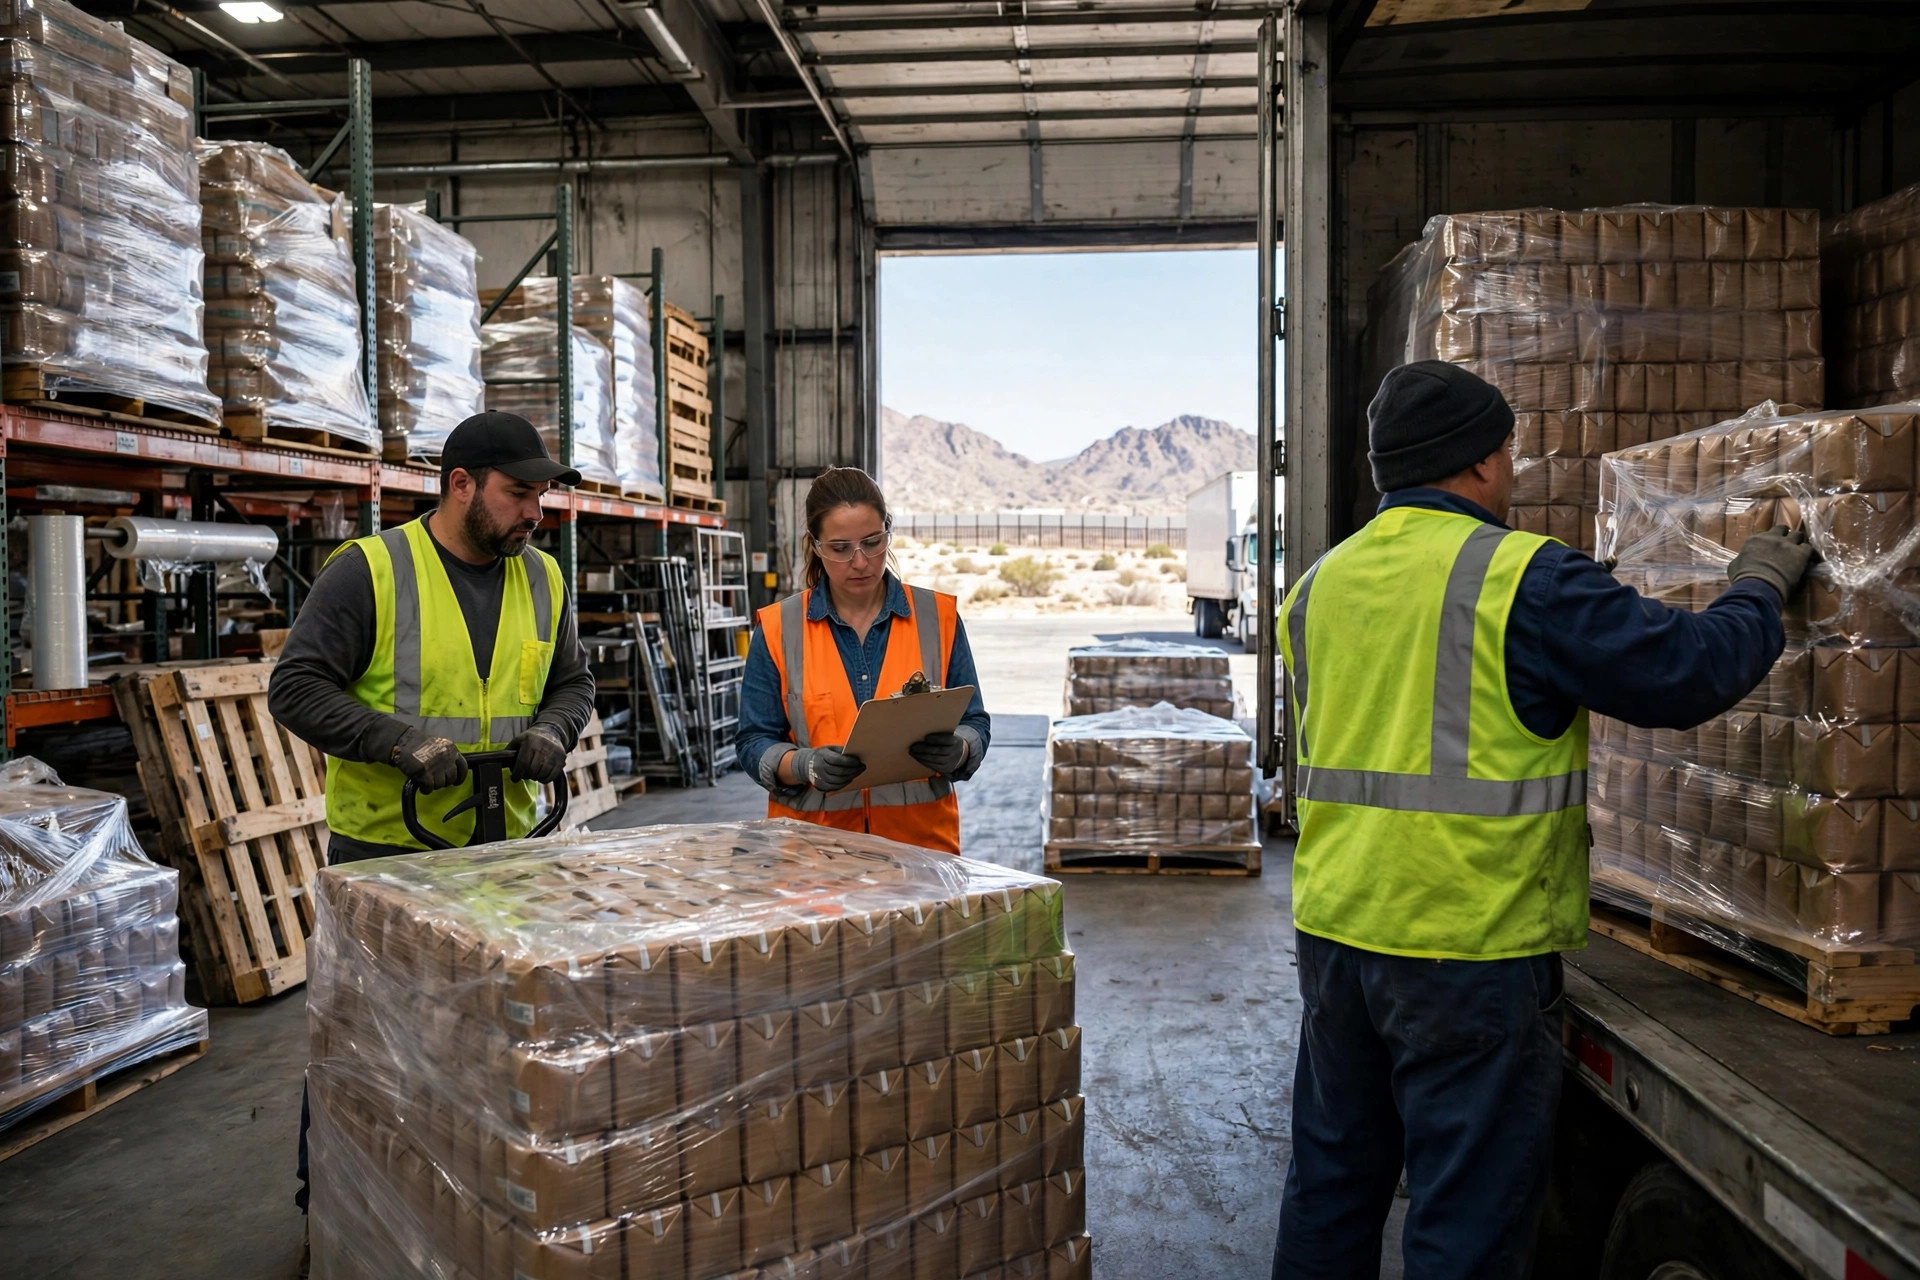
Here is the step-by-step approach I insist on. Step one: split identity at receiving. When temporarily imported material arrives, the pedimento number, part number, lot, and quantity must match the customs declaration exactly, and the system must create two logical identities even if the pallets sit side by side. Never let one stock location serve both identities. Step two: enforce physical separation. Separate zones are ideal, but at minimum use separate locations, separate pallets, and clear labeling, with barcode scanning at pick that locks the transaction if the identity is wrong. Step three: record both directions. Production issues, finished goods, scrap, and rejects must all trace back to the original pedimento. Scrap is the trap everyone underestimates. Customs loves asking about scrap, because scrap is where unrecorded domestic diversion hides. If you cannot say which import lot your scrap came from, you have a problem.
The second failure I have seen involved an injection molding plant. Yield was fine and recorded scrap rates looked reasonable, but shop-floor scrap was tossed into bins by hand and cleared at month end without lot records. When inspectors asked which temporary import lot a bin of scrap belonged to, nobody could answer. The plant ended up explaining the gap in the least favorable way possible. The rule is simple: scrap is not trash. It is part of the ledger.
Reconciling Annex 24 to your pedimentos
The Annex 24 ledger is the heart of the program, and its logic is straightforward: every temporarily imported lot opens a balance, and every movement closes part of it, whether through processing and export, authorized domestic sale with tax paid, or documented scrap and loss. The ledger balance must always equal the physical stock of temporarily imported material on hand. A gap between book and floor is a red flag.
My pre-go-live checklist looks like this. First, five fields are mandatory in the system for every line: pedimento number, date, part number, quantity, and value. A manual spreadsheet will eventually break this. Second, sample the book against the floor weekly, not at year end, and investigate differences the same day. Third, close the export loop: the export declaration for finished goods must be posted back to the original import lot, not just recorded as a monthly total. Fourth, route domestic sales and scrap through their own approval flows, with tax paid on domestic sales and evidence kept for scrap. Fifth, separate duties: the person who records a movement cannot be the same person who edits it, and every edit leaves an audit trail.
The third failure came from export reconciliation done in quarterly batches by one person. A few export declaration numbers were posted to the wrong import lines, so several lots appeared unreconciled on paper even though the goods had long since left the country. The client spent weeks producing proof. The fix is a discipline, not a tool: reconcile at export, every time, never in batches.
The annual report and the risk of losing it all
The annual report is not a year-end chore. It is the final exam for twelve months of ledger discipline. What exactly must be filed follows the current requirements of the Ministry of Economy and customs, but the core never changes: temporary imports in, out, and on hand; export reconciliation status; domestic sales and taxes paid; and closing balances. A clean ledger makes the report a summary exercise. A messy ledger turns it into fiction, and fiction does not survive inspection.
Watch the temporary admission clock, too. The commonly cited stay for temporarily imported goods is around 18 months, subject to current law, and different materials may carry different terms. I set two alarms for every lot: an early warning before expiry and a hard deadline by which the lot must be exported, reconciled, or lawfully disposed of. One overdue lot may seem small, but it damages the credibility of the entire ledger.
Use this decision framework before committing. Calculate three numbers. First, compliance cost: systems, people, and advisors. Second, tax savings: estimated from your temporary import volume and the deferred 16% VAT treatment, subject to current law. Third, risk exposure: back taxes, penalties, and downtime if something goes wrong. Proceed only if the first number is clearly smaller than the second and you are confident you can contain the third. Otherwise, get your ordinary warehouse records clean first and revisit IMMEX later.
In the end, running an IMMEX warehouse is about trust. Customs trusts your ledger, and that trust is what keeps the authorization alive. Keep identities separate, ledgers reconciled, and exports closed out on time, and the annual report stops being something to fear.
By Lin Xiao, WMS Implementation Consultant