Bottom line first: managing inventory in a bonded warehouse comes down to one rule — the customs book, the WMS book, and the physical count must agree at all times. In a regular warehouse, a 100-unit variance is an internal control issue. In a bonded warehouse, it's a customs issue. Since January 1, 2025, China's customs authority has required formal write-off (nuclear销) management of bonded logistics books (GACC Announcement No. 174 of 2024): the write-off cycle generally cannot exceed one year, and companies must file their write-off within 60 days after the cycle ends. If the book shows less than reality and you can't justify it, you pay the missing duties. If your records aren't truthful and you can't provide a legitimate reason, Article 18 of the Customs Administrative Penalty Implementation Regulations allows fines of 5% to 30% of the goods' value. This article gives you the full playbook — from book setup to write-off — plus the failure cases I've personally walked into.
Why Bonded Warehouse Inventory Books Are Different
Three differences matter:
First, every movement is declared. Goods entering the zone, leaving the zone, or transferring within it each go through a bonded filing list in the Golden Gate Phase II system. Customs keeps its own electronic ledger of your inventory. Your WMS says one number; the customs ledger says another. The two are born to be reconciled.
Second, units of measure must be singular. The customs ledger calculates in the declared unit. If your WMS tracks in pieces while customs tracks in kilograms or boxes, one wrong conversion factor poisons the whole reconciliation. I've seen this failure three times — packaging specs every time.
Third, the cost of a variance is duties and fines. In a regular warehouse you adjust a gain/loss entry and move on. In a bonded warehouse, every book-to-physical difference starts with a question: can you provide a legitimate reason? Yes — pay the duties and adjust. No — disposal "in accordance with relevant regulations," which is customs language for "this is about to get expensive."
The Step-by-Step Playbook
This is the standard sequence I run for clients implementing bonded warehouses in their WMS. Don't reshuffle it.
1. Fix the write-off cycle first, and write it into the SOP.
The announcement only says "generally no longer than one year" — companies can align the cycle with their business rhythm. My recommendation: six months. The trade-off is real. A full one-year cycle saves filing effort, but any variance means digging through twelve months of documents to trace it — one failure and you'll regret the savings. A six-month cycle doesn't quite double the workload, but it roughly halves the risk. Once decided, put the cycle cut-off date in the SOP so everyone knows it.
2. Build three mapping tables before go-live. Non-negotiable.
These are the three tables I always check on my go-live-eve checklist:
- SKU mapping: WMS SKU ↔ bonded-book SKU, strictly one-to-one, no exceptions.
- Unit-of-measure mapping: WMS unit ↔ declared unit, with conversion factors locked and decimal places standardized.
- Packaging hierarchy: pieces/cartons/cases/pallets — e.g., 1 case = 24 cartons, 1 carton = 10 pieces.
If any of the three is missing, I will stop the go-live. I've seen this hole three times, and it was always the third table.
3. Reconcile filing lists daily (T+1).
Every evening, the broker sends the day's inbound and outbound filing list numbers to the warehouse team, who tick them off in the WMS: list number, SKU, quantity, unit — all four must match. T+1 is the floor, not the ceiling. Don't batch it to the weekend; after three days of backlog, variances become untraceable.
4. Monthly cycle counts, targeted at high-variance SKUs.
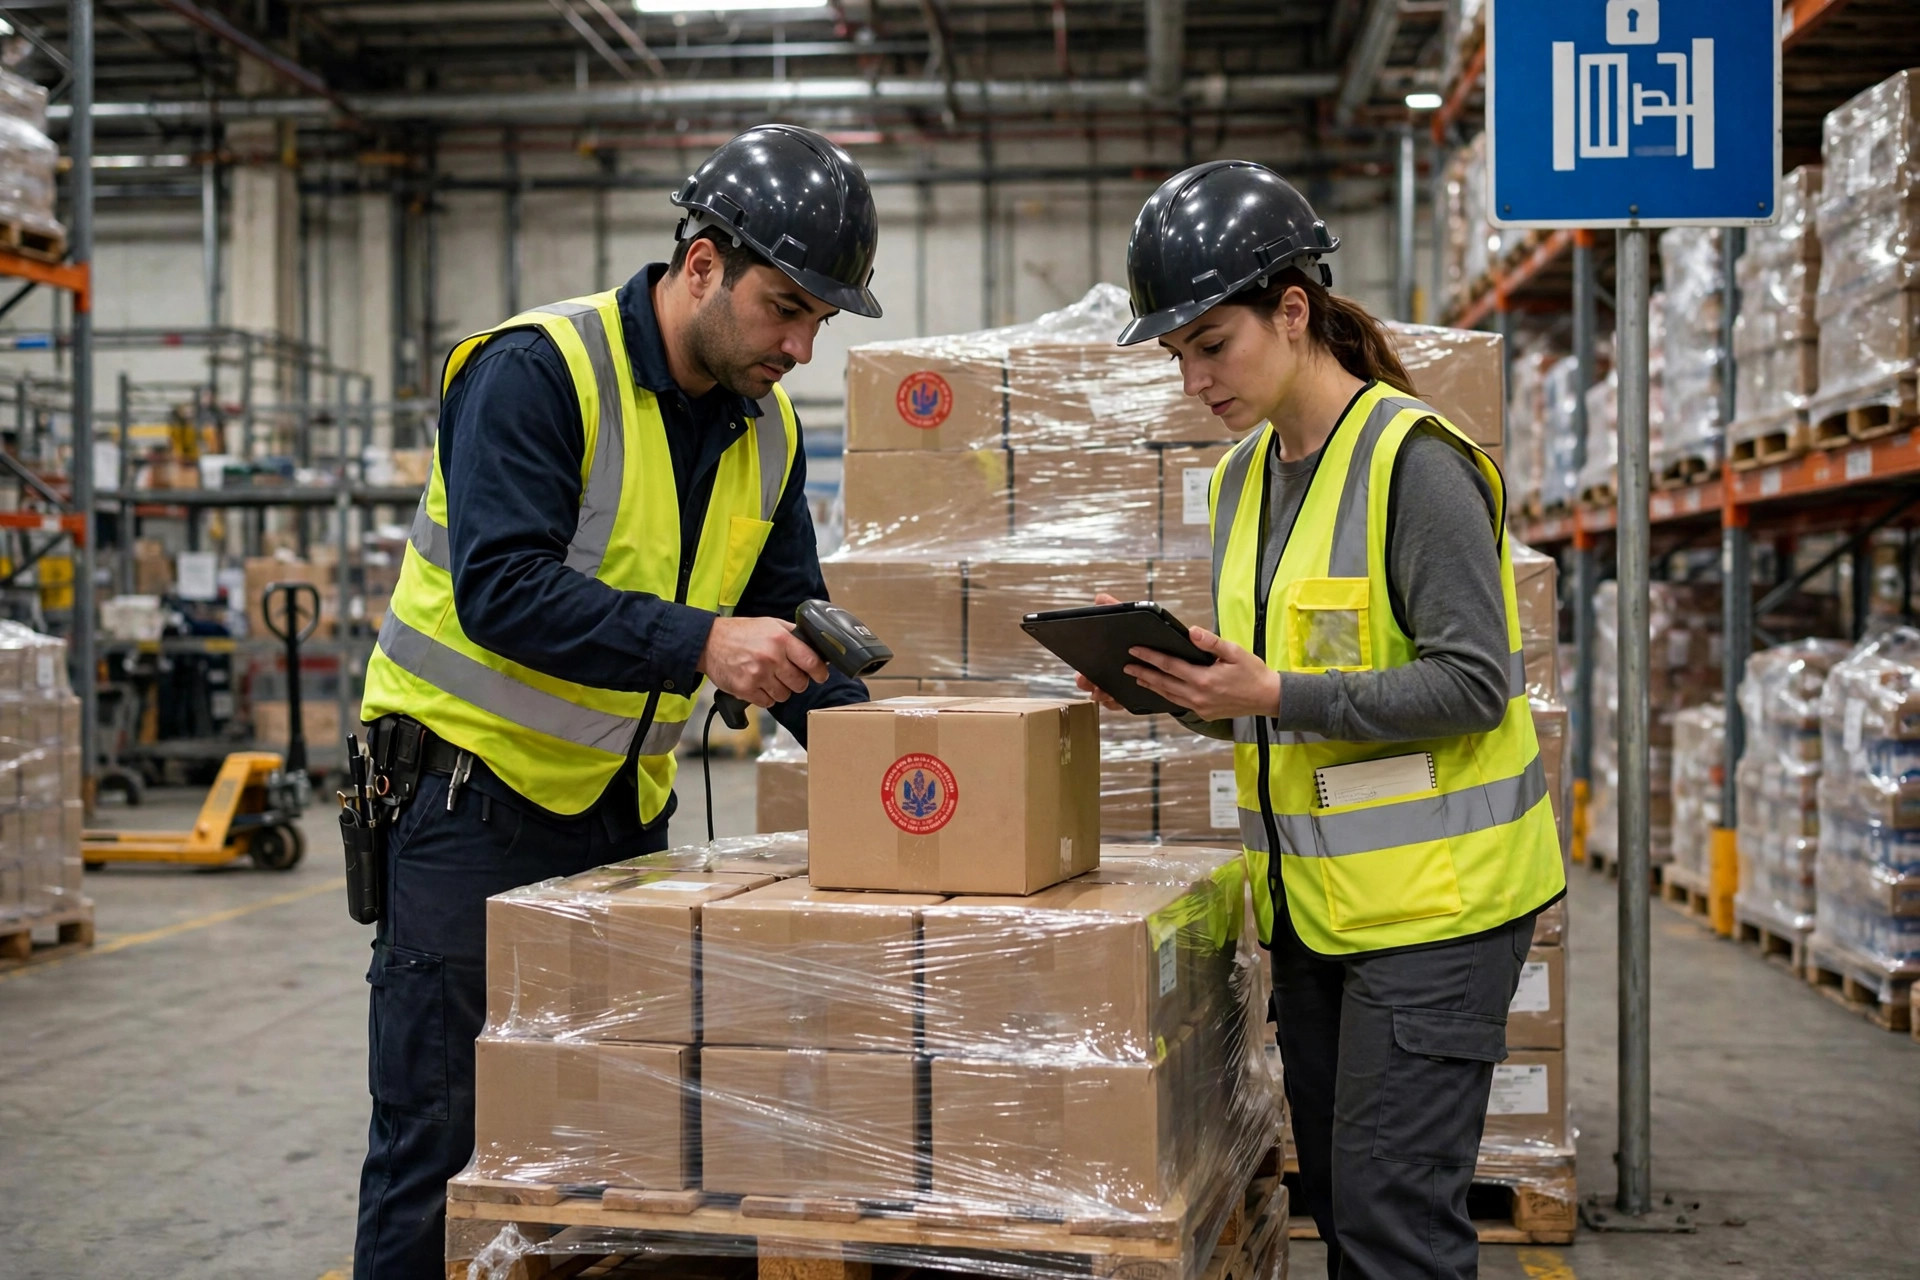
No need for a full count every month, but you must count on rotation: any SKU with last month's variance gets counted, and any high-velocity SKU gets counted. Method: WMS book quantity first, physical count second, customs electronic ledger third. Only when all three agree is the loop closed.
5. Full count before write-off, with every variance closed.
Two weeks before the cycle ends, do a full physical inventory. Every variance must be resolved before filing: find the cause, complete the documents, adjust the books. Filing a write-off with open variances is volunteering your problems to customs.
6. File within 60 days, and keep the evidence.
Within 60 days after the cycle ends, file the write-off with customs, truthfully reporting: the filing list numbers included in this cycle's accounting, the actual closing inventory, and disposition records for damaged or destroyed bonded goods. If you genuinely can't file on time, get the supervising customs office's approval for an extension — but the extended deadline cannot exceed 90 days. Keep a full copy of everything you filed, for at least three years.
Bonded Inventory Write-Off: The Four Outcomes
When customs receives your filing, it compares the electronic ledger result against your declared physical inventory. Four outcomes, four treatments (my plain-language version of the announcement):
| Comparison result | Customs treatment |
|---|---|
| Physical = electronic ledger | Filed and closed. The ideal case. |
| Physical > ledger, with legitimate reason | Ledger's current-period balance adjusted to physical |
| Physical < ledger, with legitimate reason | Duties paid on the shortfall |
| Mismatch without legitimate reason | Handled per relevant regulations |
Notice the uncomfortable truth: reconciliation cuts both ways. Many people think "more physical stock than the book" is good news — nothing was lost. Wrong. Surplus without a legitimate reason gets the same regulatory treatment. In a bonded warehouse, book-over and book-under are both problems.
Failure Cases I've Actually Seen
Failure 1: Wrong unit conversion — 1,200 phantom units on the book.
In 2024, a bonded logistics center inside an eastern China comprehensive bonded zone found its book showing 1,200 more imported connectors than the physical count during the pre-write-off inventory. Two weeks of digging later, the cause surfaced: on one outbound filing list, "cartons" had been keyed in as "pieces" — 10 pieces per carton, 120 cartons per shipment, hence 1,200 phantom units. Fortunately the outbound orders and packing lists all existed, the reason held up, and the ledger balance was adjusted to reality. The team still burned three weeks on it. Lesson: the packaging conversion table needs an independent reviewer, and the data-entry step needs a second pair of eyes.
Failure 2: Two disconnected books — two missing filing lists discovered at write-off.
A cross-border stocking client ran its WMS and its broker's Excel customs book as two parallel universes that never met. At its first write-off under the new rules in March 2025, the book came up 4,600 Bluetooth headsets short of physical stock — two inbound filing lists the broker had emailed over were never entered into the WMS. The reason was legitimate (the lists were real, just unrecorded), so duties were paid on the shortfall plus a written explanation. Since then, the client runs T+1 reconciliation. Zero incidents since.
Failure 3: Bonded and non-bonded stock stored together.
Some warehouses squeeze bonded and regular goods onto adjacent locations — sometimes even the same pallet — to save space. One mispick and both the physical and the books go sideways at once. Bonded goods must be physically segregated, and the location coding should make the distinction obvious at a glance. This one is a red line.
Failure 4: Customs seals mishandled.
Breaking or damaging a customs seal affixed to a warehouse, premises, or goods without authorization brings a warning and fines of up to 30,000 yuan under Article 23 of the penalty regulations. I once saw a forklift back into a door seal strip. Nobody reported it; it surfaced six months later at inspection and cost an extra written explanation. Paint warning lines around sealed areas — cheaper than the paperwork.
Failure 5: The 2025 old-book/new-book migration.
Since January 1, 2025, Golden Gate Phase II runs the new bonded logistics book with write-off functionality; old-version books can no longer be created, and companies had a six-month window to close out old books (by July 1, 2025). If you're opening a bonded operation now: you're on the new book from day one — don't go looking for the old setup path.
Failure 6: Missing the filing deadline.
Sixty days looks generous until the full count, variance resolution, and document preparation all pile into the final two weeks. My practice: full count two weeks before cycle end, filing done within two weeks after — keeping a full month of buffer for yourself. Filing late means applying for an extension and producing a "legitimate reason." Why volunteer for that.
One last piece of advice: bonded warehouse inventory management is won on daily reconciliation discipline, not on counting technique. A year of T+1 reconciliation beats a heroic pre-write-off count ten times over.
By Lin Xiao, WMS Implementation Consultant