If Payback Is Fuzzy, the Proposal Dies
"How fast does this pay back?" — the inevitable question in every automation approval meeting, and the easiest to fumble. Answer "about two years," get asked "show me the math," stammer — and the project is as good as dead.
Payback period itself is simple: total investment divided by annual net benefit. The devil is in the line items: omit civil works and downtime losses from costs, count "redeployed" workers as "eliminated" in benefits, and your payback looks twice as rosy as reality — then overruns and delays torch the boss's trust. This article gives you a ready-to-use ROI template: cost items, benefit items, formulas, and sensitivity analysis, step by step to a payback number that survives interrogation.
1. Cost Items: Seven Checks You Must Not Miss
Total investment has seven line items. Newcomers almost always miss the last three:
| # | Cost item | What it covers | Commonly missed |
|---|---|---|---|
| 1 | Equipment hardware | Robots, conveyors, racking | — |
| 2 | Software | WMS modules, dispatch systems, licenses | Recurring license fees |
| 3 | Implementation services | Installation, commissioning, WMS integration, training | Integration man-days |
| 4 | Civil works | Floor loading, power upgrades, network, fire protection | Power upgrades cost most |
| 5 | Downtime losses | Capacity lost during implementation | Doubles if done in peak season |
| 6 | Spares | First spares batch, safety stock | — |
| 7 | First-year operations | Maintenance contract, power, consumables | Power is often forgotten |
Rule of thumb: actual total ≈ quoted price × 1.2. The quote covers items 1–3; the remaining four typically add 15–25%. Put a "contingency (10%)" line in the template — bosses find it reassuring, not alarming.
2. Benefit Items: Four Benefit Types, No Double Counting
Annual benefits come in four types. Don't double-count:
- Labor savings: eliminated headcount × fully loaded annual cost. Key: only count heads truly eliminated — redeployments to other departments are "freed up," not "saved"; only unfilled attrition counts. Model conservatively at 70% of replaceable headcount.
- Error reduction: error-rate improvement × annual volume × cost per error. Cost per error = return freight + reshipment + service cost + churn allocation.
- Capacity/revenue uplift: new capacity from automation × gross margin per unit. Only counts if capacity actually becomes orders — idle capacity is not a benefit.
- Other: space savings (less leased area), energy reduction (freezer cases), fewer injuries, compliance value.
Annual net benefit = sum of the four − annual operating cost (maintenance + power + consumables + software fees).
3. Core Formulas: Payback, ROI, NPV
| Metric | Formula | Reading |
|---|---|---|
| Payback period | Total investment / annual net benefit | Years to break even |
| ROI | Annual net benefit / total investment × 100% | Annualized return % |
| NPV | Discounted N-year benefits − investment | > 0 means viable; for large projects |
| IRR | Discount rate where NPV = 0 | Viable if above cost of capital |
Small and mid-size projects need only the first two. Example: $444K invested, $278K annual net benefit → payback 1.6 years, ROI 62.5%. For ten-million-plus projects, add NPV with the company's cost of capital (typically 8–12%) as the discount rate.
4. Template Design: Ready to Use
Turn the cost and benefit items above into a spreadsheet — that's your ROI template:
Sheet 1: Investment
- Column A: the seven cost items (equipment, software, implementation, civil works, downtime losses, spares, first-year ops, 10% contingency)
- Column B: amounts; Column C: basis/notes; total at the bottom = total investment
Sheet 2: Benefits
- Labor savings: eliminated headcount × annual cost × 70% (conservative factor)
- Error reduction: error-rate improvement × annual volume × cost per error
- Capacity uplift: new capacity × margin per unit (needs sales sign-off)
- Other: space/energy/safety
- Less: annual operating cost → annual net benefit
Sheet 3: Results
- Payback, ROI, NPV auto-computed
- Sensitivity table (next section)
Template discipline: every number gets a "basis" column — headcount from HR, error rates from WMS, unit costs from finance. Numbers without a basis get picked apart in the meeting.
5. Sensitivity Analysis: Answering the Boss's "What If"
The boss will ask: "What if we can't save that many people?" "What if the equipment is late?" Sensitivity analysis prepares the answers in advance:
| Scenario | Annual net benefit | Payback |
|---|---|---|
| Base | $278K | 1.6 years |
| Pessimistic (benefits −30%) | $195K | 2.3 years |
| Optimistic (benefits +20%) | $333K | 1.3 years |
| Investment +20% overrun | $278K on $533K | 1.9 years |
Say the key conclusion out loud: "Even in the pessimistic case — benefits at 70% — payback is 2.3 years, still inside the 3-year line." That one sentence beats any equipment spec.
Case Study: ROI Workup for an AGV Project
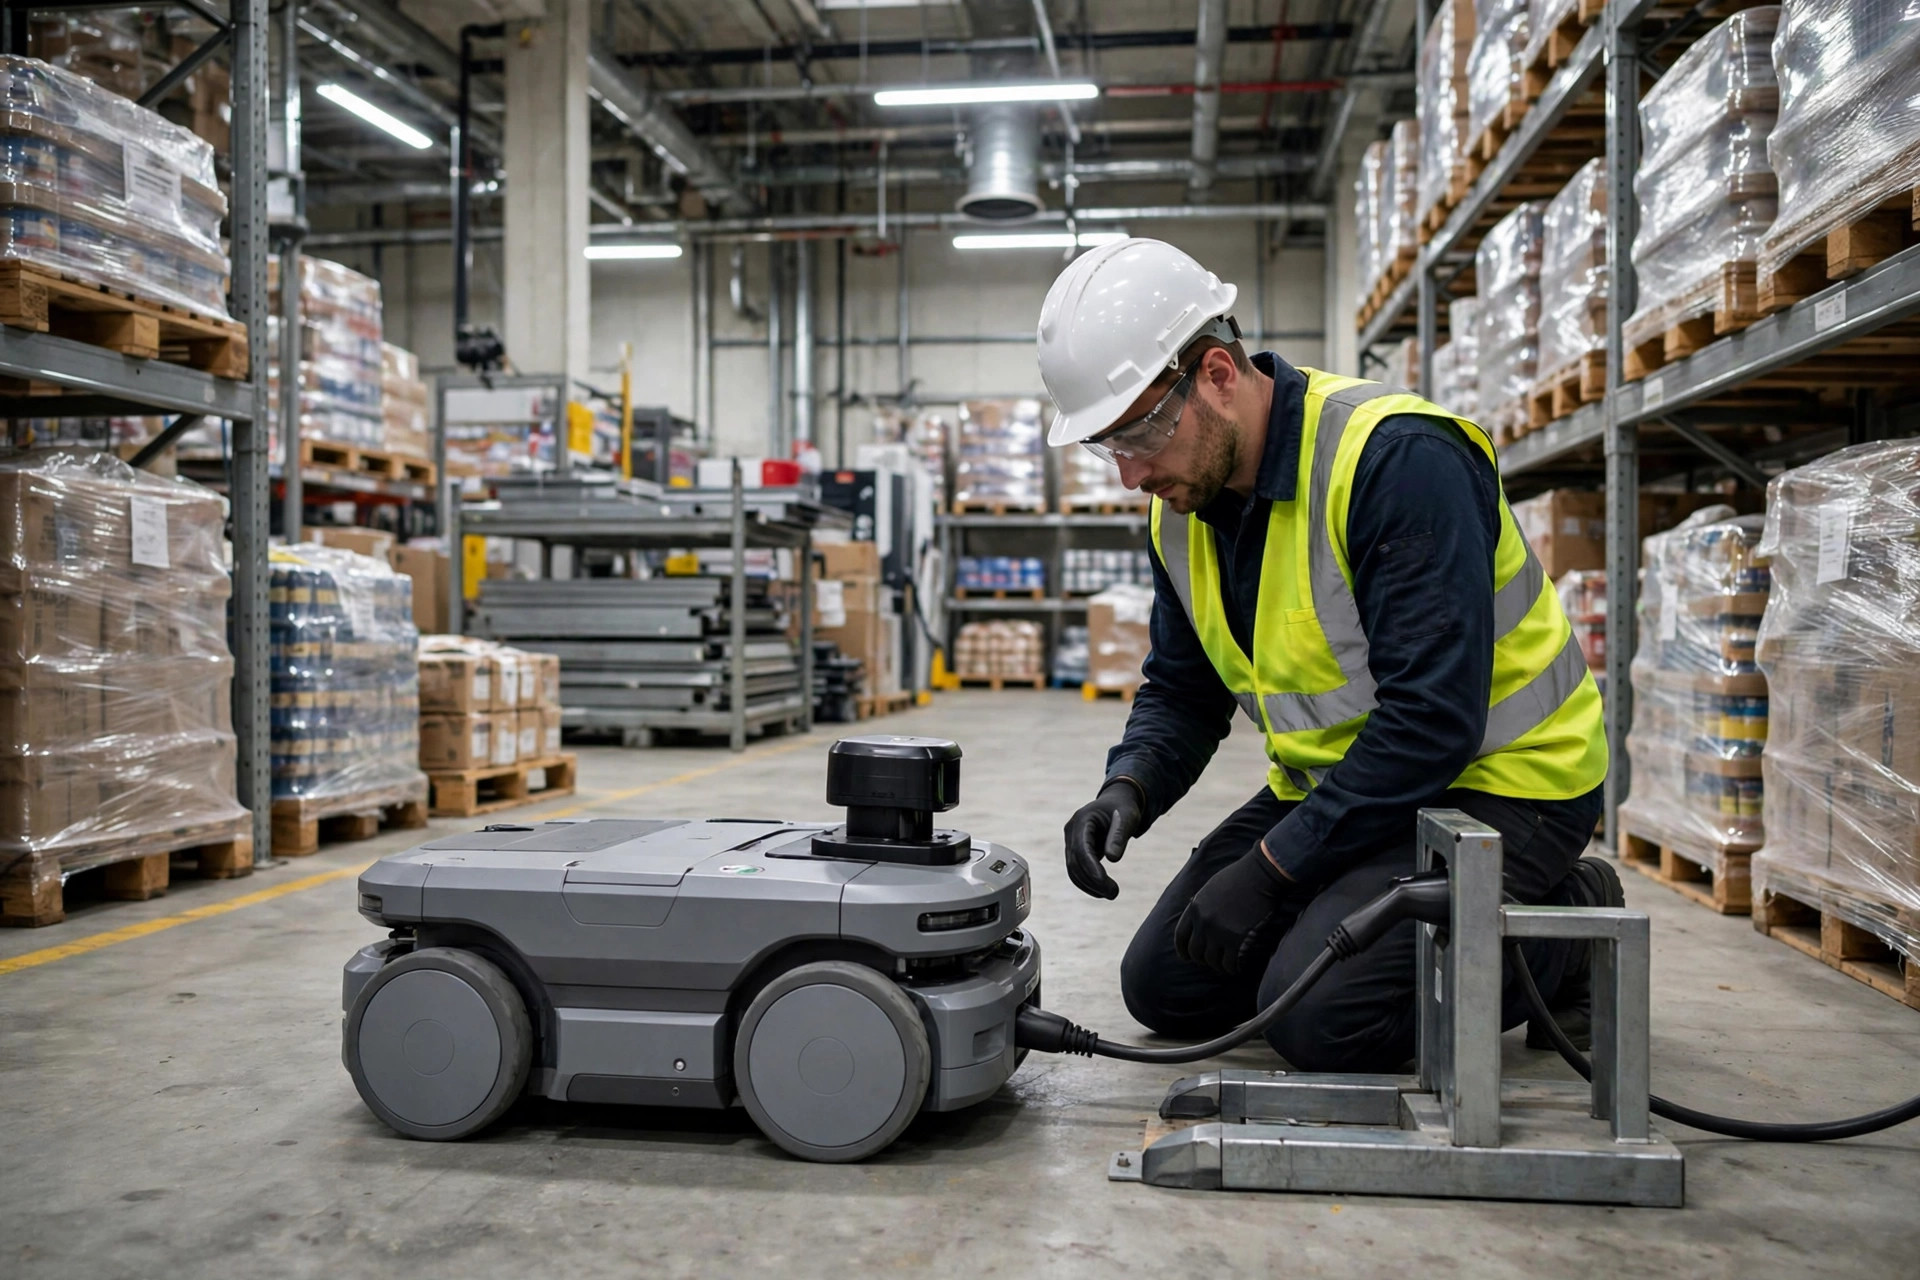
Background: a 3C manufacturing warehouse moving materials to production — 8 AGVs replacing 12 forklift operators.
Investment: AGV hardware $389K + dispatch system $35K + implementation $21K + floor/network rework $25K + first-year maintenance $17K + 10% contingency = $535K.
Annual benefits: labor 12 × $21K × 70% = $175K; injury/downtime reduction $35K; forklift fuel/maintenance $42K; total $252K. Less $49K annual ops → annual net benefit $203K.
Result: payback = 535 / 203 ≈ 2.6 years, ROI 38%. Sensitivity: pessimistic (benefits −30%) → 3.8 years, slightly over the 3-year line — disclosed honestly in the report, paired with a two-phase risk-reduction plan. Approved.
Pitfalls
- Counting redeployments as cuts: the most common inflation. Saved heads must mean "positions eliminated, never rehired" — internal transfers are reshuffling, not savings.
- Omitting annual operating cost: maintenance contracts, power, consumables, software fees — tens of thousands a year, small or large. Skip them and the payback is fiction.
- Modeling on peak capacity: 365 days at full tilt is fantasy; 70% utilization is realistic. Use historical utilization; peak-season spikes are reference only.
- Ignoring cost of capital: on ten-million-plus projects, skipping NPV is malpractice. The company's borrowing cost (8–12%) is the hurdle rate — IRR below it means the project loses money.
Takeaway
The ROI template is three sheets: investment (seven items + 10% contingency), benefits (four types − annual ops), results (payback + ROI + sensitivity). Document the basis for every number, haircut benefits 20%, inflate investment 20%, and keep the pessimistic payback inside 3 years — a payback computed that way is hard for any boss to poke holes in. Templates are static; rigor is what makes them work: the more conservative the math, the smoother the project.